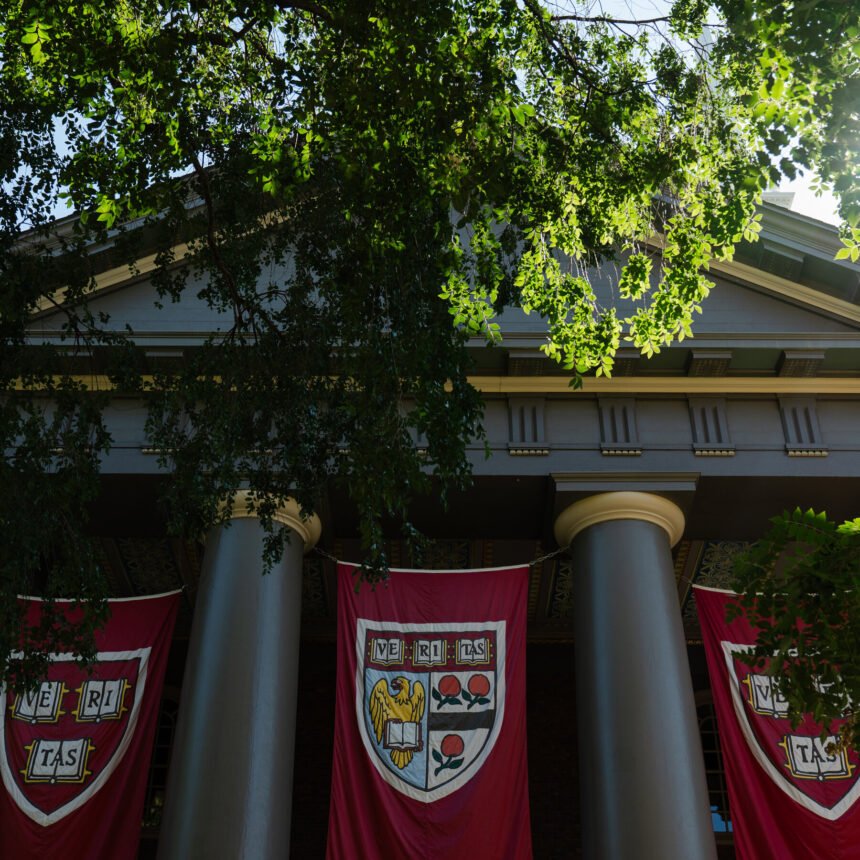
The Treasury Department has unveiled a series of regulatory amendments that could render several educational institutions ineligible for their prized tax-exempt status, specifically those implementing programmes that target minority students. This sudden shift in federal policy threatens the bottom line of many academic bodies and private schools, effectively placing the financial health of these organisations up against the clock. As the administration refines its approach to equity and discrimination, the implications extend far beyond simple compliance checks, touching upon the core operations and sustainability models of the American education sector.
A Fundamental Policy Realignment
The crux of the matter lies in a proposed interpretation of anti-discrimination statutes that extends the reach of existing laws into the realm of academic aid. According to the latest guidance, any educational establishment offering financial support—whether through scholarships, grants, or institutional subsidies—that is visibly tied to racial categories risks losing its designation as a non-profit organisation. The Treasury has argued that such measures constitute an illegal form of protectionism, favouring specific ethnic groups over others regardless of individual merit. Consequently, institutions which have historically relied on race-conscious initiatives to attract diverse student bodies now face a precarious legal exposure that demands immediate recalibration of their financial structures.
From a corporate governance perspective, this is a watershed moment. For decades, the interplay between state funding and tax law has provided a stable framework for growth. Now, that stability is being tested by a rigid stance on demographic data. The message is clear: the pursuit of equality cannot come at the cost of fiscal solvency. Universities and private academies must now navigate a maze of compliance that requires them to prove that every dollar of aid serves a purely academic purpose, devoid of any cultural or ethnic undertones. Failure to achieve this precise balance could result in immediate penalties, mandated reforms, and a significant erosion of their tax shields.
Divergent Challenges for Public and Private Entities
The impact of these rules varies significantly depending on whether the affected body falls under public jurisdiction or operates independently. State-run universities typically face the sharpest cuts, given their reliance on federal tax breaks to offset the enormous overheads associated with infrastructure and faculty salaries. When the IRS deems a programme to be “discriminatory,” the consequence is often a massive surge in taxable income. This forces a difficult trade-off: either absorb the additional tax liability or scramble to raise funds from outside sources, potentially leading to increased tuition hikes that alienate prospective students.
Independent schools present a different, yet equally challenging, scenario. These entities often thrive on philanthropy and donor relationships rather than government subsidy. However, the pressure to diversify their funding streams remains intense. For a school whose primary revenue comes from a narrow base of wealthy donors, the introduction of tax levies could jeopardise the very endowments that sustain their long-term vision. The financial burden of compliance—requiring extensive record-keeping, third-party audits, and legal consultations—may also divert resources away from the classroom, forcing administrators to make tough decisions about where to cut costs.
Moreover, the narrative surrounding these policies frames the debate not merely as a matter of finance, but of principle. Critics argue that the ruling places an undue burden on private institutions, arguing that they lack the same scale of influence as government bodies when enforcing civil rights. Proponents counter that the original intent was to curb well-intentioned but poorly managed welfare schemes that disproportionately stigmatised minority communities. The tension between these two ideological camps adds another layer of complexity to the financial calculus facing school leaders today.
Strategic Responses and Future Outlook
In light of this changing landscape, many academic leaders are already beginning to articulate their contingency plans. The conversation has shifted toward the restructuring of aid models. There is a growing movement within the sector to pivot towards “need-blind” admissions and holistic review processes that prioritize academic potential over demographic origin. This strategy aims to maintain the social mission of the institution while stripping away the explicit markers of identity that triggered the regulatory red flag.
For private schools, the response is more pragmatic. Many are exploring alternative funding avenues, such as diversified corporate partnerships or endowment reallocations, to mitigate the risk of rising tax assessments. The market is reacting swiftly, with analysts warning that the uncertainty surrounding tax-exempt status could dampen investment flows into certain sectors. Institutional investors are increasingly wary of the “hidden costs” embedded in compliance, viewing them as a drag on overall enterprise value.
Looking ahead, the trajectory seems directional. As the Treasury fine-tunes its guidelines, we can expect a wave of legal challenges and legislative pushback. However, for now, the immediate reality is one of heightened vigilance. The era of unchecked racial prioritisation in academic funding appears to be drawing to a close, replaced by a stricter regime where transparency and objective criteria reign supreme.
Why it Matters
The repercussions of this policy shift reverberate through the entire ecosystem of higher education, threatening to destabilise the delicate balance between equity mandates and fiscal sustainability. As the Treasury moves forward with these stringent enforcement measures, the financial burdens imposed on institutions will inevitably trickle down to the students they serve, potentially altering the accessibility of quality education. The battle to preserve tax-exempt status becomes a proxy war for the soul of American academia, where the fight is not simply against bureaucracy, but against a rigid adherence to past precedents that no longer aligns with modern economic realities.