Five Bankers’ Convictions Overturned After Court Finds Trials Unfair
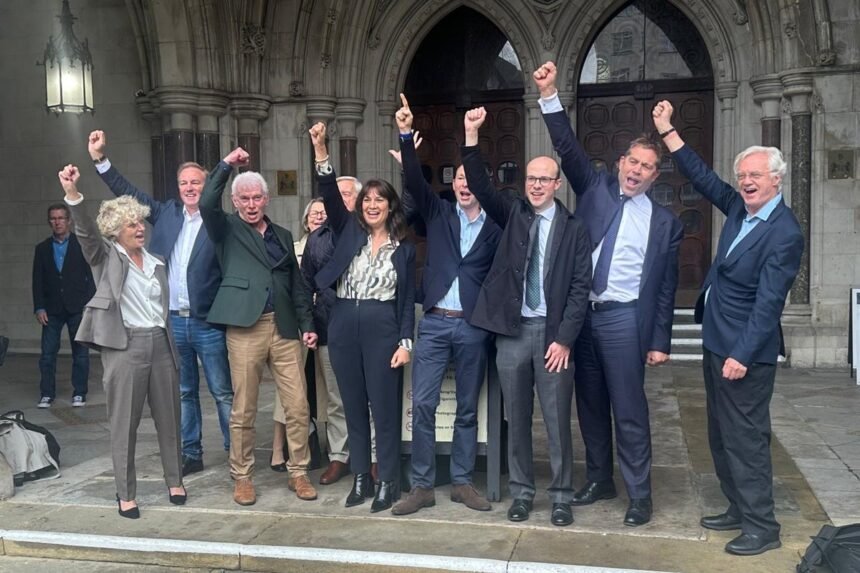
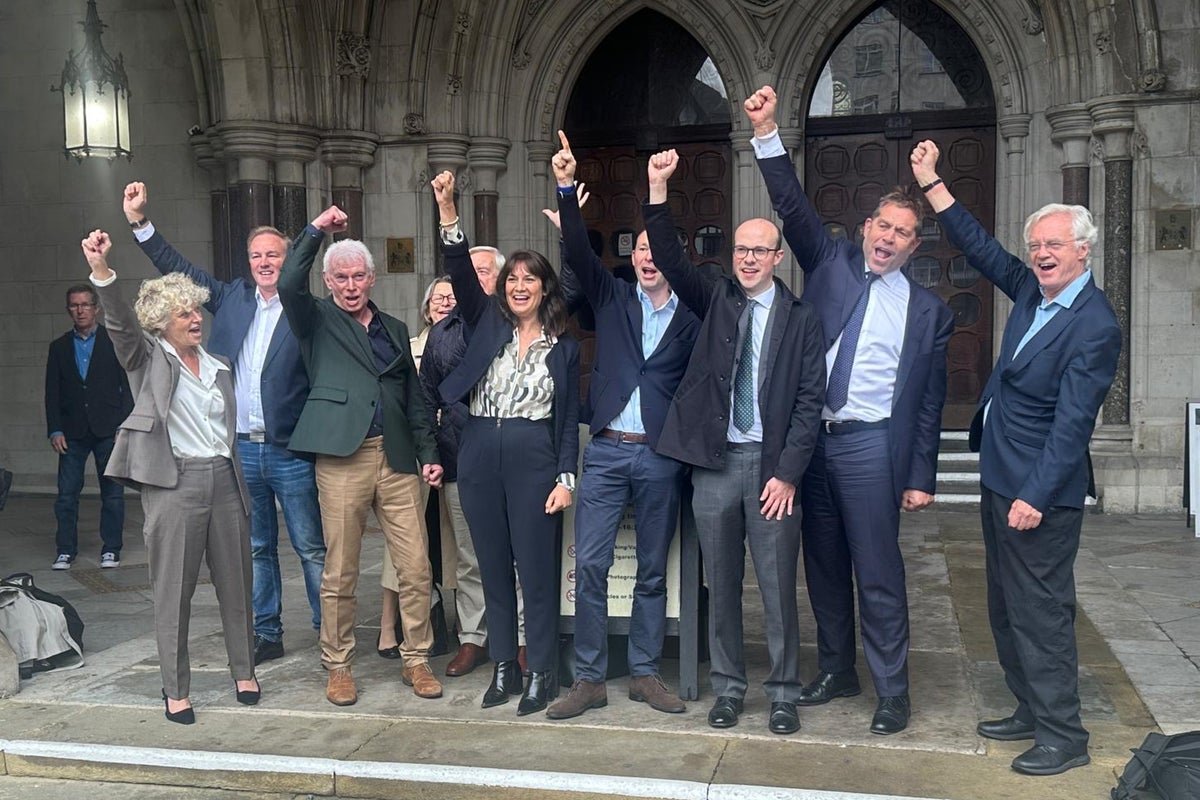
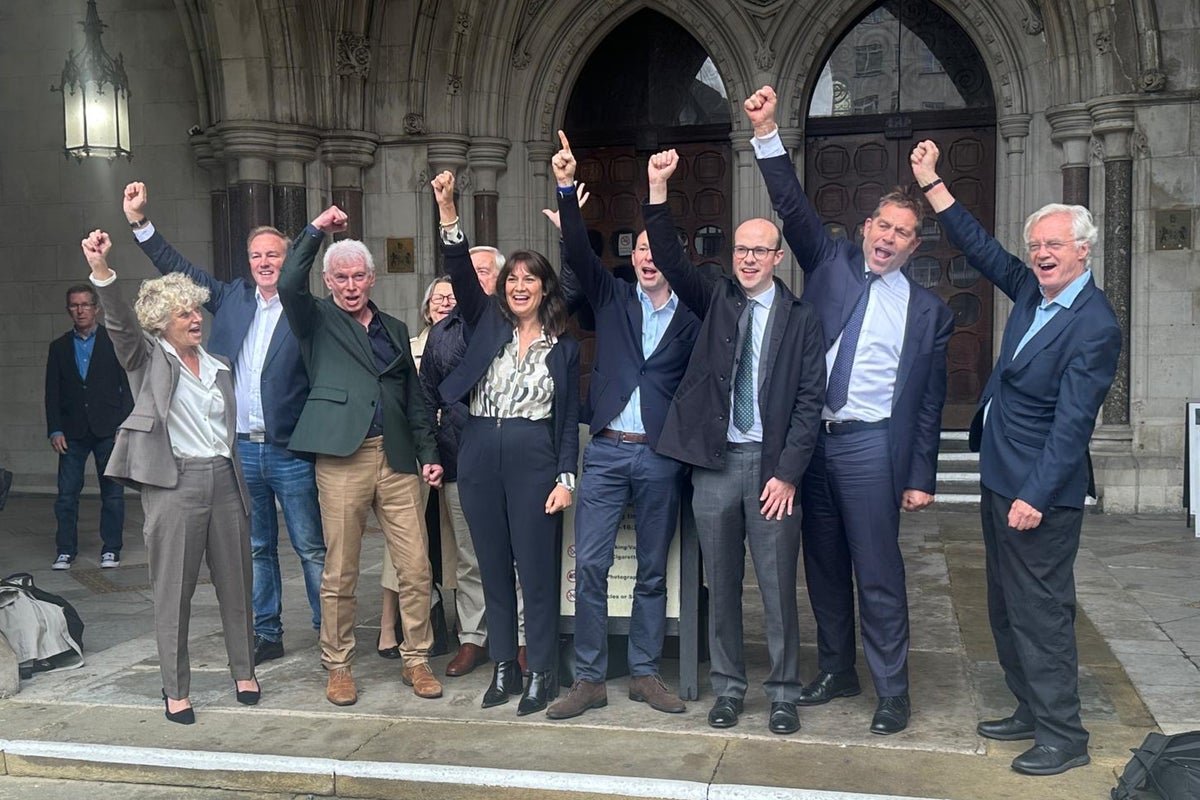
A series of high-profile prosecutions targeting bankers accused of rigging global interest rate benchmarks have taken a sudden turn. Five former Barclays employees—Jonathan Mathew, Jay Merchant, Alex Pabon, Philippe Moryoussef, and Colin Bermingham—whom previous courts sentenced to prison terms ranging from two years to nearly six years, now find their convictions set aside entirely. The Court of Appeal has quashed their verdicts on Wednesday after determining that critical errors plagued their trials, revealing a fundamental flaw in the proceedings that rendered the entire legal journey invalid.
The Wrong Turn That Changed Everything
What emerged during the latest hearing was a clear pattern of procedural missteps that had poisoned the very foundation of five separate trials. Legal representatives for the defendants argued with conviction that the jury instructions handed to the jurors bore a striking resemblance to those crafted for the case of Tom Hayes—a trader whose conviction was already quashed by the Supreme Court earlier this year. This uncanny similarity raised serious questions about whether the courts had applied consistent standards across different cases, potentially undermining the fairness of the outcomes.
Lord Justice Edis, presiding alongside Justices Goose and Moody, ultimately concluded that the same erroneous direction had crept into the proceedings against the five men. The Court of Appeal determined that the errors were not isolated incidents but rather systemic failures that compromised the legitimacy of their convictions. As counsels for the defence put it in written submissions, the appellants’ common complaint centered on parallel legal deficiencies that originated in the initial trial setup itself. When the same flawed methodology was reused—or inadvertently replicated—in the appeals process, the difference became starkly apparent.
Personal Toll and Release
Beyond the courtroom drama, the human cost of these convictions has been profound for each individual and their loved ones. For Jay Merchant, described in his statement as having carried “the stain of a criminal conviction” for the past decade, the quashing of his sentence represents more than just an academic correction—it carries the weight of years spent in prison, lost wages, and a fractured sense of self-worth. He expressed gratitude to his family for supporting him through the darkness, noting that having the conviction overturned was not merely about restoring his record but about finding validation that a grave injustice never truly occurred.
Philippe Moryoussef shared a similarly transformative perspective. Having fled to France after his conviction, he spoke of experiencing a complete loss of employment, professional reputation, and even income. The moment his case was cleared, he said he was able to “regain his soul” and imagine a future chapter without the shadow of incarceration looming. His testimony underscored the deeper, psychological scars that accompany such wrongful convictions, transforming a legal dispute into a deeply personal reckoning with identity and dignity.
A Financial Infrastructure Under Investigation
The manipulation of interest rate benchmarks such as the London Inter-Bank Offered Rate (Libor) and the Euro Interbank Offered Rate (Euribor) represented one of the most significant regulatory challenges of recent decades. These rates served as crucial reference points for billions of pounds in financial transactions worldwide, influencing everything from mortgage agreements to large-scale industrial projects. For years, traders within major banking groups had allegedly colluded to artificially sway these figures above market levels, thereby capturing unwinnable margins on loans and derivatives contracts.
When the investigation uncovered the scope of the collusion, authorities launched prosecutions against twenty individuals between 2013 and 2019. Seven of those suspects were eventually convicted at trial, while others either pleaded guilty or walked free. The scale of the operation meant that ordinary citizens borrowing homes or financing business expansions unknowingly relied on calculations built upon manipulated data. The exposure of these practices sparked widespread concern about the stability of global markets and the integrity of banking oversight.
What Comes Next
While the quashing of the five men’s convictions marks a significant victory for those accused, legal teams have indicated that further proceedings remain open. Christian Bittar, another individual convicted in connection with the Libor scandal, is scheduled to have his own appeal heard separately, though his conviction currently stands. Meanwhile, the Serious Fraud Office continues to emphasise its commitment to pursuing the most serious cases of financial fraud and corruption. The Department’s head confirmed that the recent decisions reflect careful consideration of both judicial principles and public interest considerations.
As the legal pendulum swings toward clarification, experts suggest that the case could serve as a cautionary tale for future trials involving complex financial instruments. The consistent application of jury directions—and the rigorous testing of those procedures—stands as a benchmark for maintaining trust in the judicial system. Whether these findings inspire stricter safeguards or prompt reforms elsewhere, the immediate impact is clear: thousands of economic relationships built upon shaky foundations may now face reassessment.
Why it Matters
The reversal of these convictions underscores the vital importance of procedural rigor in any tribunal dealing with matters of national and international significance. When the machinery of justice contains even minor flaws—such as using identical legal instruction templates across disparate cases—their cumulative effect can undermine the credibility of entire investigations and inflict lifelong hardship on innocent parties. This case demonstrates that the pursuit of truth requires vigilance, transparency, and an unwavering commitment to fairness, lest the scales of justice tip too heavily onto the shoulders of the wrongly punished.
For the wider community, the outcome serves as a reminder that financial systems depend on honest actors operating within them. Manipulation of benchmark rates does not merely affect banks; it erodes confidence among consumers, destabilises markets, and invites heightened scrutiny from regulators everywhere. By acknowledging the errors and rectifying them, the judiciary not only sets a precedent for the five men but also reinforces the broader moral contract upon which modern finance rests. The restoration of their reputations and futures highlights how restorative justice extends beyond legal technicalities—it touches hearts, careers, and the everyday security of countless ordinary people who rely on the soundness of the markets in which they live.