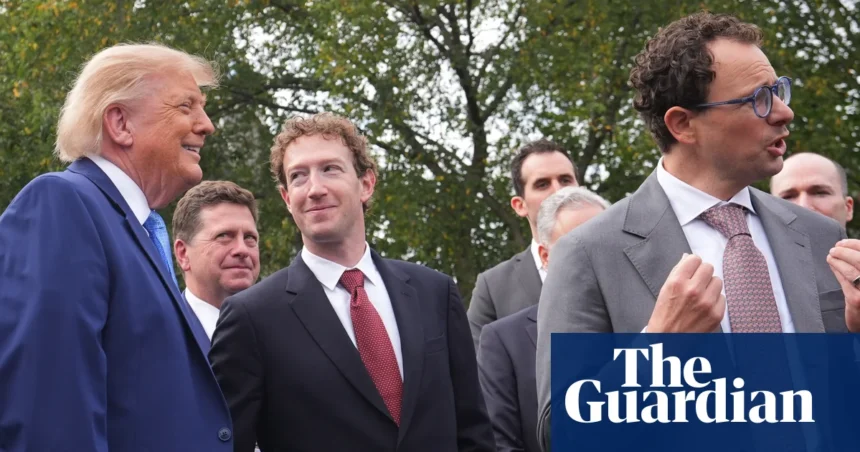
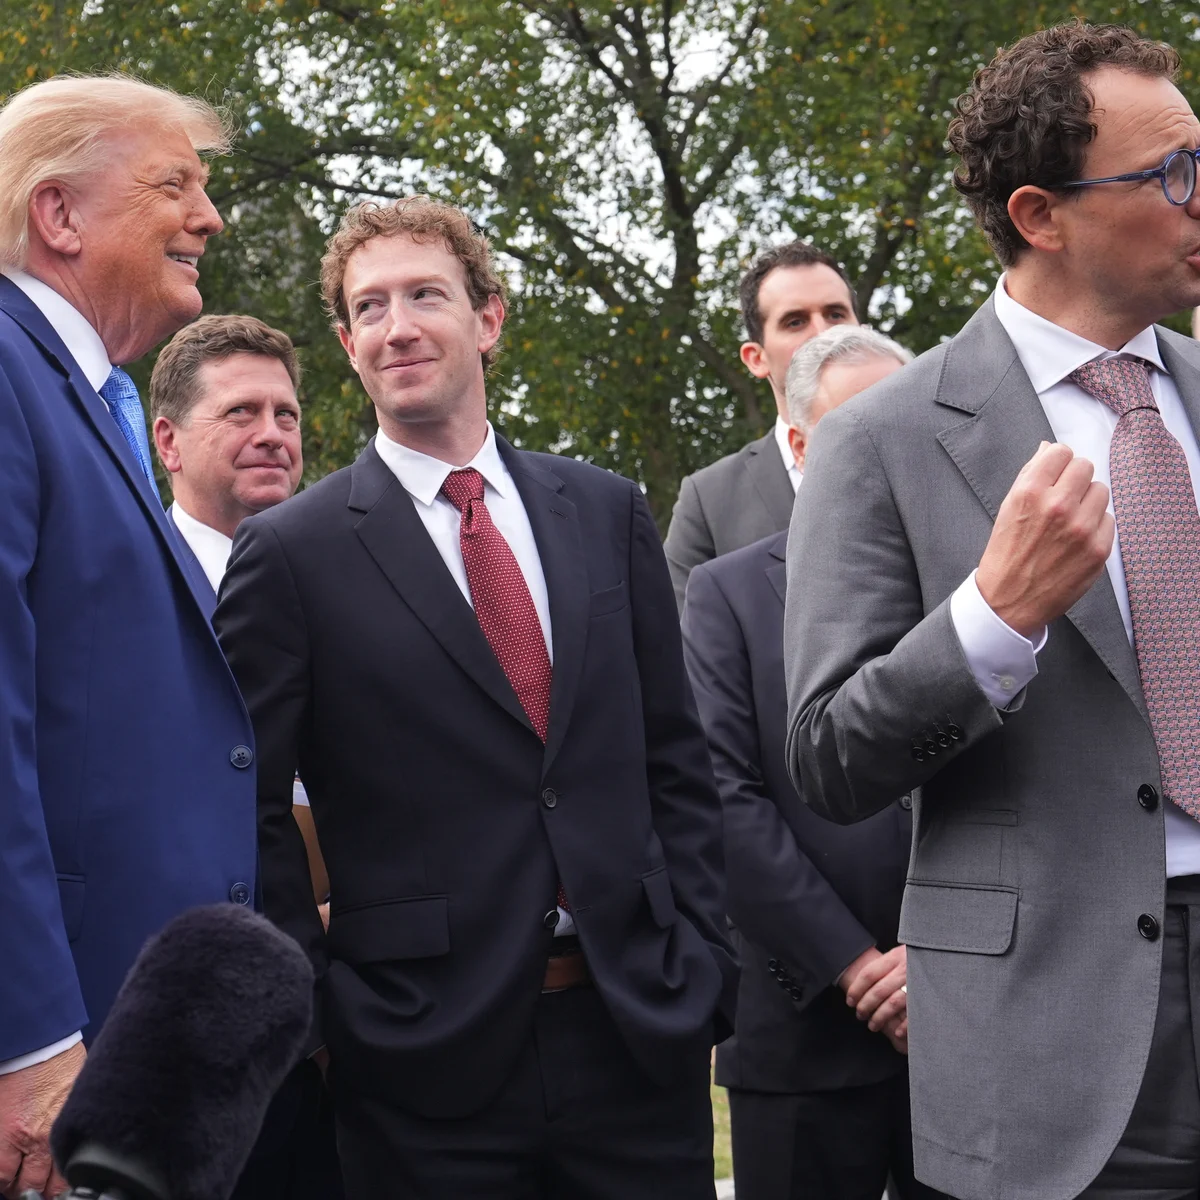
The White House is betting the farm on artificial intelligence. Standing alongside Mark Zuckerberg and Anthropic’s Dario Amodei last month, Donald Trump insisted the US economy would soon grow “at a faster rate than we’ve ever grown before” – fast enough, he claimed, to chip away at a $40 trillion federal debt mountain. His Treasury Secretary, Scott Bessent, has put a number on it: three per cent annual growth, a threshold breached only twice this century outside the post-Covid rebound. Financial markets, however, have already delivered their verdict. The yield on the 10-year Treasury has climbed to its highest level in nearly a quarter-century, more than a full percentage point above where it sat when the President launched his ill-fated conflict with Iran.
The Return of Supply-Side Fairy Dust
This is a story Washington has told itself before. Since Ronald Reagan’s first term, Republicans have insisted that tax cuts pay for themselves by unleashing explosive growth. The Gipper’s promise didn’t pan out. Neither did George W. Bush’s. Or Trump’s own 2017 package. Each round of cuts deepened the deficit. Now the same argument has been dusted off and coated in what Eduardo Porter aptly calls “AI pixie dust” – the conviction that machine intelligence will rewrite the laws of fiscal arithmetic.
The problem isn’t just that history rhymes. It’s that the arithmetic has become brutal. Interest payments on the federal debt now consume 3.3 per cent of GDP, up from a fifty-year average of 2.1 per cent. The “One Big Beautiful Bill Act” – the administration’s signature legislative achievement – is projected to add $4.7 trillion to the debt through 2035. The deficit already sits at six per cent of GDP, double what Bessent once pledged. The Congressional Budget Office sees it approaching seven per cent by 2033. And that was before the President promised a $5,000 “dividend” to every American adult if Republicans hold Congress in the midterms.
Bond Markets Deliver Their Verdict
Investors are not waiting for the midterms to price in the risk. The surge in long-term yields reflects two colliding forces. The immediate trigger is inflationary pressure from the Iran conflict, which forced the Federal Reserve to hike short-term rates. But the structural driver is simpler: the US Treasury is running out of natural buyers.
Foreign central banks, once reliable accumulators of Treasuries for reserve management, have been quietly reducing exposure. That leaves private investors – hedge funds, pension funds, insurers – who demand a proper risk premium. Worse, the Treasury now finds itself competing for capital with the very AI hyperscalers it is counting on to deliver the growth miracle. Google, Meta, Microsoft, Oracle, SpaceX and Amazon are borrowing heavily to finance datacentre build-outs. Every basis point their borrowing costs rise is a basis point the government pays too.
The Math That Doesn’t Work
The Committee for a Responsible Federal Budget has run the numbers. Assume the 2025 tax cuts become permanent – a safe bet, given historical precedent – and assume the revenue lost when the Supreme Court struck down the national security tariffs never returns. To bring the deficit down to three per cent of GDP by 2036 would require 4.4 per cent annual growth for a decade. A balanced budget would demand 7.2 per cent.
Those figures assume the growth translates into tax revenue. It might not. AI’s most plausible economic effect is a massive shift of income from labour to capital. Capital is taxed at roughly half the effective rate of labour. Even if the pie grows enormously, the government’s slice could shrink. And a labour-displacing boom would almost certainly demand massive new spending to support displaced workers – a fiscal double bind.
Stabilising the debt-to-GDP ratio would require total factor productivity growth of 2.5 per cent annually for ten years. The US has hit that mark once since 1959 – and that was despite the combined tailwinds of electrification, the interstate highway system, the telecoms revolution and the first wave of IT. Betting on lightning striking twice is not a fiscal strategy. It’s a prayer.
When AI Investment Competes With Uncle Sam
The private sector’s own numbers ought to concentrate minds. Stanford’s Hanno Lustig calculates that datacentre operators need 45 per cent annual revenue growth for seven straight years just to break even on this year’s estimated $1.43 trillion in AI capital expenditure. By 2032, that revenue would equal 9.2 per cent of GDP. A separate analysis by Jared Bernstein and Ryan Cummings puts the ten-year revenue gap for the six hyperscalers at $13.1 trillion to $18.7 trillion – roughly equivalent to their entire combined revenues over the past decade.
Missing those targets wouldn’t just hurt tech stocks. It would leave a trail of stranded assets, impaired bank balance sheets, and a Treasury still desperate for buyers. The AI boom, in other words, is currently tightening the very financial conditions the White House needs to ease.
Why it Matters
The administration has constructed a fiscal strategy that requires miracles: unprecedented productivity growth, a historic shift in the tax base, and private investment returns that defy recent precedent – all while borrowing costs climb and the buyer base for US debt shrinks. If the AI revolution delivers even a fraction less than the utopian scenarios, the deficit trajectory becomes unsustainable without either brutal austerity or monetary financing. Markets have already started pricing that risk. The question is whether Washington will recognise it before the next crisis forces the issue.