The quiet panic is spreading through suburban streets and city planning offices alike. As the annual renewal season approaches, countless households are discovering that their properties are no longer safe havens but rather expensive liabilities. Soaring premiums have transitioned from a standard line item in a household budget to a primary source of anxiety, marking the height of an ongoing midterm affordability battle. Driven by a stark increase in severe weather events, the industry is witnessing a perfect storm of inflation and catastrophe, leaving millions of homeowner without affordable coverage.
The Climate Catalyst: From Peril to Premium
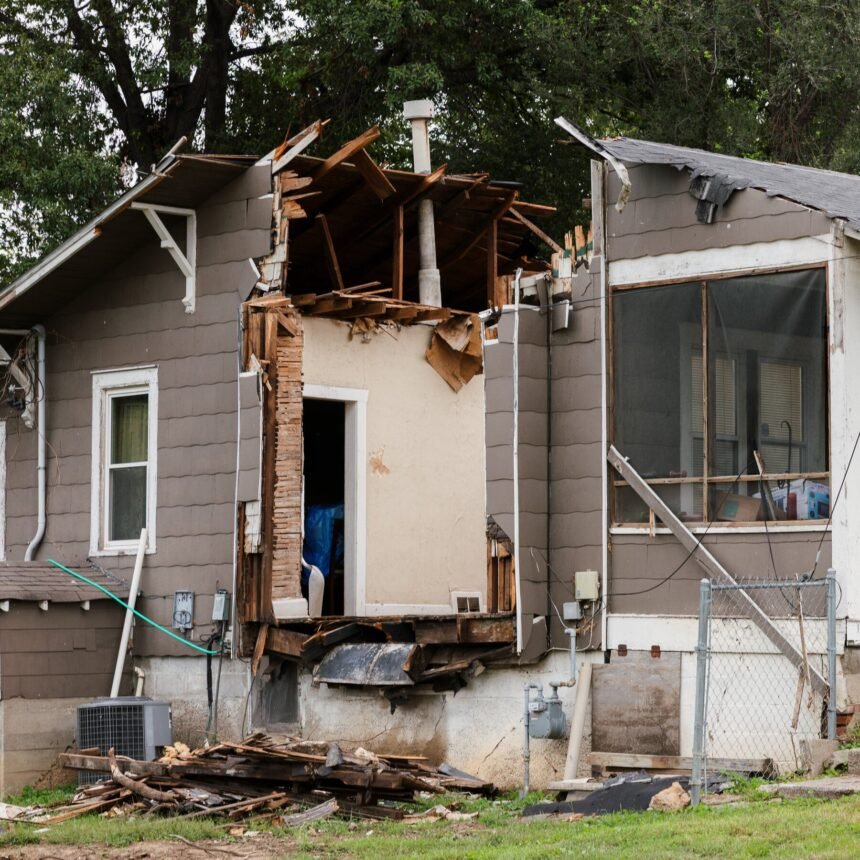
The engine behind this pricing paradox is undeniably climatic. For decades, actuaries relied on historical data to predict risk, but the last few years have shattered those assumptions. Extreme heatwaves in the western states, relentless wildfires, and the resurgence of tornado outbreaks in the central United States have collectively created a landscape of unprecedented instability.
In California, the blaze season has become a near-constant presence. Insurers are re-evaluating exposure models with alarm, leading to sharp increases in coverage costs for residential properties. Similarly, across the heart of the country, Tornado Alley is experiencing seasonal fluctuations that are far more volatile than previously anticipated. These events are not merely natural occurrences; they are economic shocks that ripple through the financial system, causing insurers to recalibrate risk assessments and, consequently, hike the monthly bills for thousands of voters.
The data speaks clearly: the correlation between disaster frequency and pricing power is absolute. Where once one could rely on stable rates for two decades, the modern homeowner faces a volatile market where the future is dictated by the latest NOAA forecast. This shift is accelerating the decline of the “standard” homeowner, pushing an increasing number of families into the precarious state of being under-insured or entirely uncovered.
A Geography of Grief: Regional Disparities in Risk
The impact of this crisis is not distributed evenly across the map. While the West and the South bear the brunt of wildfire smoke and seismic activity, the central plains are seeing a surge in claims that threatens to destabilise local economies.
Regional disparities highlight a fractured understanding of risk management. High-risk zones, particularly in wildfire-prone counties, are witnessing a dramatic compression of the insurance marketplace. Some jurisdictions have seen their protected areas shrink to a fraction of their former size. Meanwhile, regions less prone to direct fire but vulnerable to flooding and wind storms—such as parts of the Northeast and Midwest—are also facing pressure, though often in different guises.
This geographical fragmentation creates a patchwork of affordability. A family in a coastal town may find themselves paying double what a neighbour in a low-risk zone pays for identical coverage. This disparity fuels public frustration, transforming insurance from a utility into a political football. As the election calendar tightens, the struggle for fair access to cover is becoming a potent wedge issue, with voters demanding that policymakers intervene to prevent a total collapse of the protection ecosystem.
The Political Crossroads: Regulation versus Market Realities
Nowhere is the tension more apparent than in the halls of capitols and the boardrooms of major underwriters. This is, after all, the “New Affordability Fight,” and the debate has moved beyond mere economics into the realm of legislative red tape.
On one side of the aisle stands the advocacy group calling for immediate, aggressive intervention. They argue that the current market fails the vulnerable, citing soaring premiums as evidence of a broken system that demands urgent government oversight. Legislators are proposing measures such as forced purchase programmes and subsidies to shield middle-income brackets from financial ruin. However, these proposals face a formidable wall of opposition rooted in skepticism.
Critics of such interventions worry about the “moral hazard” inherent in subsidised risk. There is a fear that artificially lowering costs would incentivise builders to construct flammable structures in high-risk zones, knowing they would avoid the full cost of prevention. For these opponents, the solution lies in stricter building codes and better urban planning—a long-term approach that offers no immediate relief to the current crisis. Instead, they advocate for voluntary reforms that respect market discipline.
Yet, even within the bipartisan discourse, the reality is stark. The sheer volume of claims generated by extreme weather is overwhelming the existing infrastructure. The argument is simple: if the private sector cannot manage its exposure effectively, there must be a collective response. We are currently witnessing a clash between the desire for rapid, comprehensive solutions and the slow-moving machinery of bureaucracy, a stalemate that leaves homeowners scrambling for coverage before their letters arrive.
Why it Matters
Beyond the immediate financial strain on consumers, this escalation signifies a profound shift in the relationship between property and public security. When the cost of shelter exceeds the capacity of the private market to support it, the notion of housing as a basic right is fundamentally challenged. It represents a critical juncture where the interplay of climate science, economic policy, and political will will determine the stability of the domestic sector for generations to come.