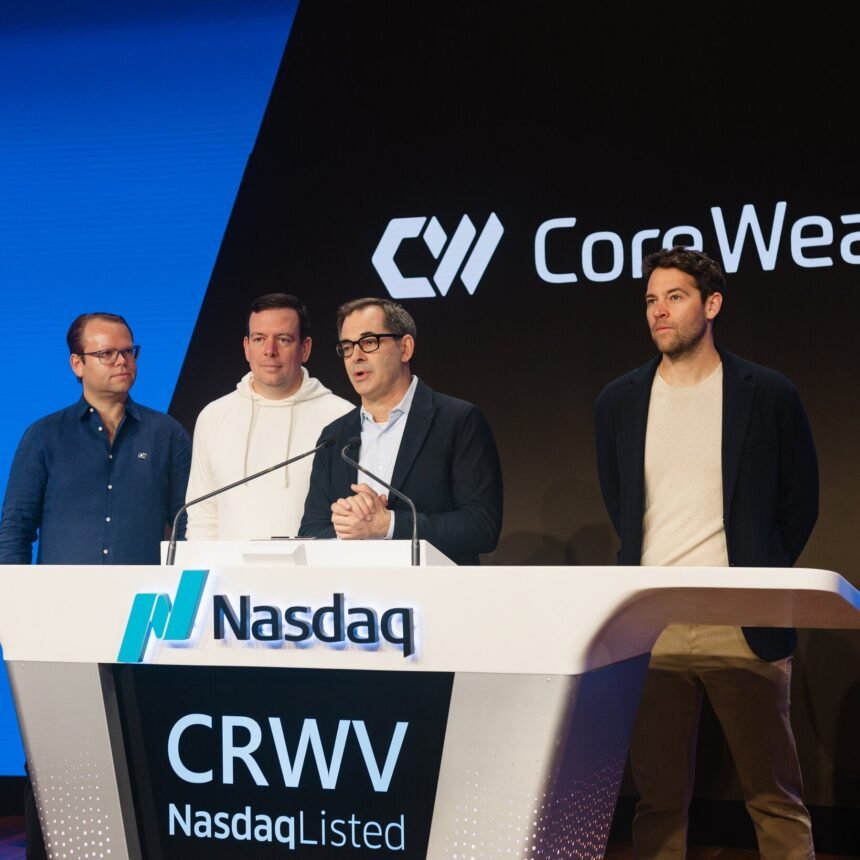
A sharp market downturn dubbed the “Neocloud” collapse has sent shockwaves through the technology sector, leaving investors increasingly wary of the financial health of AI infrastructure firms, with CoreWeave emerging as a focal point of concern. The episode has sparked a broader reassessment of the sector’s profitability prospects and the sustainability of the capital flows that have driven recent growth.
Rising Investor Anxiety
Market participants are now scrutinising balance sheets and cash‑burn metrics across the AI‑infrastructure space. Recent filings and analyst briefings suggest that the once‑robust demand for high‑performance GPU‑based services has begun to soften, prompting a wave of profit‑taking. Venture‑capital firms that previously competed aggressively for stakes in emerging infra‑players are now adopting a more cautious stance, demanding clearer paths to profitability before committing additional capital. This shift in sentiment is being felt not only in the United States but also among European and Asian investors who have shown growing interest in AI‑driven data‑centre projects.
CoreWeave in the Spotlight
CoreWeave, a leading provider of cloud‑based AI computing resources, has become the bellwether for the sector’s health. The company’s recent efforts to secure a substantial financing round have been met with heightened due‑diligence, as lenders and equity investors question the sustainability of its growth model. Industry sources indicate that CoreWeave’s revenue expansion, while impressive, is increasingly dependent on a narrow client base and the continued availability of cutting‑edge graphics processing units. Analysts point to the firm’s reliance on a handful of large technology contracts as a potential vulnerability, especially if those clients decide to bring more of their workloads in‑house or shift to competing platforms. The company’s chief executive has publicly affirmed confidence in its roadmap, yet the market’s reaction to the latest funding discussions underscores the fragility of investor confidence at the moment. Observers note that CoreWeave’s ability to diversify its customer portfolio and secure longer‑term supply agreements for GPU hardware will be critical in restoring market tranquillity.
Ripple Effects Across the AI Supply Chain
The fallout from the “Neocloud” episode is rippling beyond CoreWeave, affecting a broader ecosystem of hardware manufacturers, software platforms, and specialised AI‑infrastructure providers. Companies such as Run:AI, Cerebras Systems, and Graphcore have seen their stock valuations come under pressure as investors re‑evaluate the entire value chain. Hardware suppliers, which have been ramping up production of advanced GPUs to meet AI demand, are now confronting slower order books and potential overcapacity. This slowdown could lead to a temporary pause in capital expenditure plans, potentially delaying the rollout of new AI models and services that rely on these processing units. Moreover, cloud service providers that have built dedicated AI‑optimised environments are reassessing their cost structures, which could translate into higher prices for end‑users or a slowdown in the pace of AI adoption across industries. The collective tightening of financing conditions is prompting a more disciplined approach to investment, with a focus on operational efficiency and clear revenue trajectories.
What Wall Street Is Watching
Financial markets are now parsing a range of indicators to gauge the depth of the current turbulence. Trading volumes in AI‑infrastructure related stocks have risen sharply, reflecting heightened speculation and risk‑off sentiment. Analysts are monitoring key metrics such as gross margin trends, customer acquisition costs, and the rate of new contract signings. Additionally, the performance of related exchange‑traded funds and the spread between high‑yield and investment‑grade debt for tech‑focused infrastructure firms are being watched as barometers of broader credit health. Institutional investors are also reviewing their exposure to AI‑related ventures, with some considering a temporary reduction in allocations until clearer signs of stabilisation emerge. The consensus among market participants is that the sector’s long‑term fundamentals remain intact, but that a period of consolidation and tighter capital discipline is likely before growth resumes at previous rates.
Why it Matters
The “Neocloud” collapse has laid bare the interdependency between AI’s rapid ascent and the financial resilience of the infrastructure that powers it. While the immediate impact is felt most acutely in the valuations of firms like CoreWeave, the broader implications touch on the speed at which artificial intelligence can be commercialised across sectors, the cost trajectory for AI services, and the confidence of both public and private capital providers. A prolonged funding crunch in this niche could slow innovation, force companies to prioritise short‑term profitability over long‑term R&D, and ultimately temper the transformative potential of AI technologies. Conversely, a swift recalibration of business models and a return to disciplined growth could strengthen the sector’s foundation, setting the stage for more sustainable expansion. Investors, policymakers, and industry leaders are therefore closely monitoring these developments, recognising that the health of AI infrastructure is not just a niche concern but a pivotal factor shaping the next wave of technological advancement and economic growth.