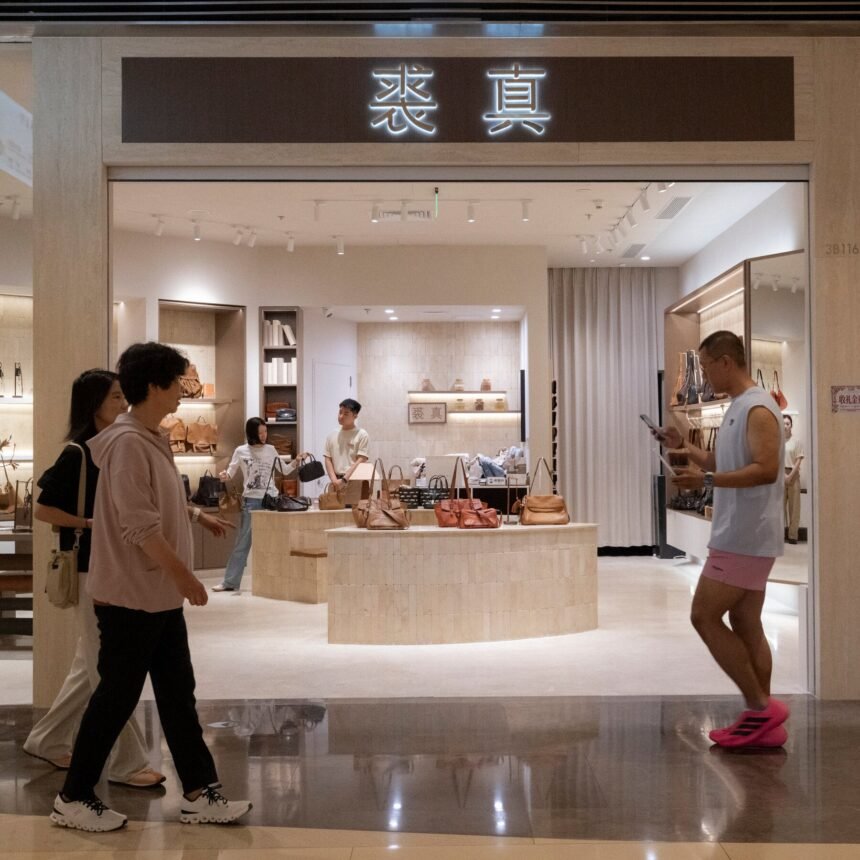
Despite a deepening housing crisis, tepid consumer demand, and declining domestic investment, China’s economy continues to post respectable growth figures—thanks largely to a robust export sector that is shouldering an increasingly heavy load.
Exports Carry the Load
While factories across Europe and North America have struggled with supply chain disruptions and energy shortages, Chinese manufacturers have capitalised on global demand for electronics, machinery, and consumer goods. Data from the General Administration of Customs shows that China’s export volumes rose 15.7% year-on-year in the first nine months of 2023, reaching $2.8 trillion. This surge has provided a crucial buffer against faltering domestic conditions.
But the reliance on external markets is becoming more pronounced. Internal data reveals that net exports now contribute over 60% of China’s GDP growth this year—a dramatic shift from previous decades when consumer spending and infrastructure investment were the primary drivers.
Housing Market Crisis Deepens
The property sector, once the backbone of China’s economic miracle, shows few signs of recovery. Home prices in major cities have fallen for 23 consecutive months, according to the National Bureau of Statistics. Major developers like Evergrande and Country Garden continue to grapple with massive debt burdens, leaving millions of unfinished projects and dampening consumer confidence.
“We’re seeing a complete collapse in buyer sentiment,” said Zhang Wei, a senior analyst at Beijing-based Merchants Securities. “Until policymakers address the structural issues in the housing market, domestic demand will remain subdued.”
Consumer spending has followed a similar trajectory. Retail sales grew just 3.2% annually in August, well below the government’s target of 5%. With household wealth eroding and employment uncertainty rising, Chinese consumers are prioritising savings over spending.
Investment Slows Across Key Sectors
Fixed-asset investment—the traditional engine of Chinese growth—has declined by 4.5% year-to-date, marking the steepest drop since the pandemic began. Infrastructure spending, long used as a stimulus tool, has lost momentum as local governments face tighter fiscal constraints and mounting debt obligations.
The manufacturing sector presents a mixed picture. While export-oriented industries thrive, domestic-facing segments such as automotive and textiles report falling revenues. Factory gate prices have been in deflationary territory for eight straight months, signalling weak internal demand and intense price competition.
Policy Response Remains Cautious
Beijing has introduced targeted measures to stabilise the economy, including interest rate cuts and relaxed home-buying restrictions in select cities. However, economists argue that these steps fall short of the comprehensive reform programme needed to rebalance growth toward consumption and services.
Financial markets have taken note. The yuan has weakened against the dollar this quarter, raising concerns about capital outflows and imported inflation. Meanwhile, global investors are watching closely as China’s export strength influences commodity prices and trade dynamics worldwide.
Why it Matters
China’s growing dependence on exports underscores a critical vulnerability in the world’s second-largest economy. As the property crisis drags on and domestic demand remains fragile, the sustainability of current growth rates comes into question. For global markets, a resilient Chinese export machine offers some relief amid widespread economic uncertainty—but any disruption to this delicate balance could have far-reaching consequences for supply chains, commodity markets, and international trade relations.