With just a fortnight remaining until voters render their verdict, the contest for control of Congress has crystallised into a high-stakes duel defined by contradictory signals and stubbornly tight margins. Republicans remain favourites to reclaim the House, yet the path to a Senate majority has narrowed to a handful of hyper-localised knife fights where candidate quality and turnout operations may matter more than the national mood. As the calendar flips to October 19, strategists in both parties are conceding that the final fifteen days will likely be decided not by sweeping narratives, but by the gruelling mechanics of ground games in Pennsylvania, Georgia, Nevada, and Arizona.
The House: A Red Tide Meets Structural Resistance
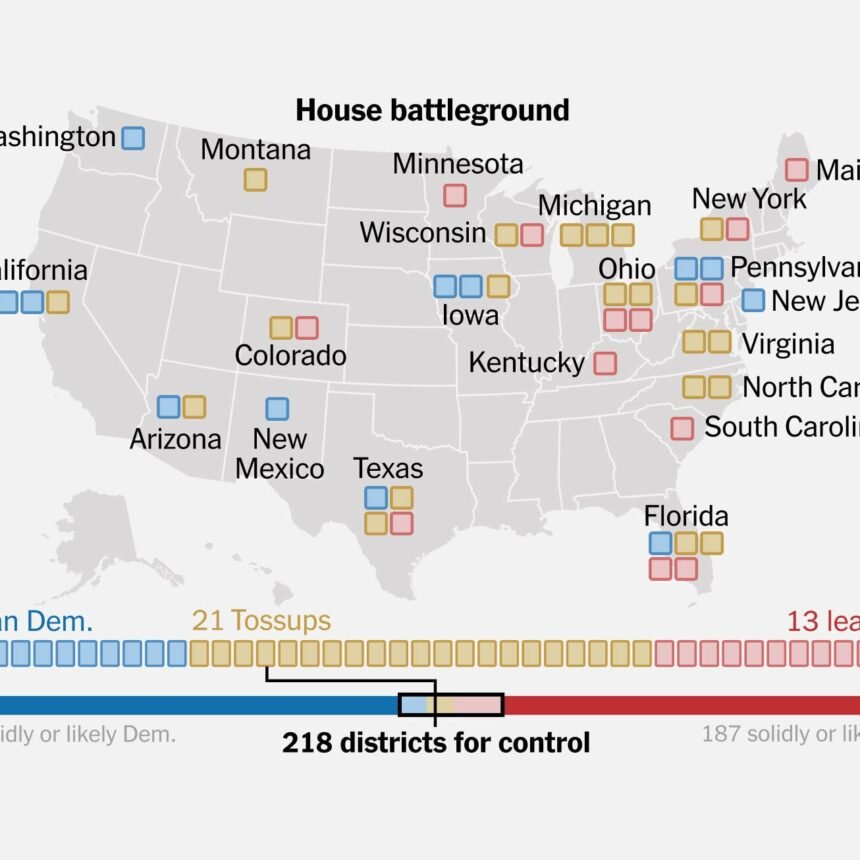
The conventional wisdom has held for months: the party out of power typically gains ground in a first midterm, and historical precedent suggests a Republican takeover of the lower chamber is the baseline scenario. Internal polling across the National Republican Congressional Committee points to a net gain of somewhere between 15 and 30 seats — comfortably above the five-seat threshold required to install Kevin McCarthy as Speaker. Yet the geography of the battlefield has complicated the arithmetic.
Democrats have poured resources into defending incumbents in Biden-won districts from Long Island to the Central Valley of California, while simultaneously mounting credible offensive challenges in Republican-held seats across Nebraska, Iowa, and New York’s Hudson Valley. The Supreme Court’s decision to overturn Roe v. Wade injected a volatile variable into suburban districts where college-educated voters — particularly women — have shown a willingness to split tickets.
Strategists on both sides now describe the House landscape as a “layer cake” rather than a wave. In Washington state’s 3rd District, Republican Joe Kent is locked in a dead heat with Democrat Marie Gluesenkamp Perez. In Alaska, Mary Peltola’s special election victory has forced the GOP to defend a seat they assumed was safe. These anomalies suggest the Republican majority, should it materialise, may be slender — perhaps as narrow as a three-to-five seat margin. That reality is already shaping McCarthy’s calculus, forcing him to negotiate with the House Freedom Caucus before he has even secured the gavel.
The Senate: Candidate Quality and the Walker Factor
If the House race is a volume game, the Senate is a series of high-stakes poker hands. The map was always unforgiving for Republicans: they are defending open seats in Pennsylvania and Ohio while challenging incumbents in Nevada, Arizona, Georgia, and New Hampshire. Yet the GOP’s recruitment struggles have turned winnable races into toss-ups.
Nowhere is this more acute than in Georgia, where Herschel Walker’s candidacy has become a daily crisis management exercise for Senate Minority Leader Mitch McConnell. Allegations regarding the former football star’s personal conduct have dominated the airwaves, forcing the campaign to divert resources from persuasion to damage control. Senator Raphael Warnock, meanwhile, has built a formidable financial advantage and a turnout operation calibrated to the state’s new election laws.
In Pennsylvania, John Fetterman’s stroke recovery has dominated coverage, but Dr. Mehmet Oz’s inability to close the gap in a state Biden carried by 1.2 points speaks to deeper Republican vulnerabilities. Nevada offers the GOP their clearest pickup opportunity, where Adam Laxalt is locked in a grinding battle with Senator Catherine Cortez Masto in a state where the Democratic machine, built by the late Harry Reid, remains potent. Arizona’s Blake Masters has struggled to pivot from a primary fought on the hard right to a general electorate that rejected Kari Lake’s gubernatorial bid in the polls.
The Senate map, in short, has become a referendum on candidate quality — a theory McConnell articulated privately months ago and which the polling now validates.
The Economic Crosscurrent
Inflation remains the dominant issue for the electorate, consistently polling as the top concern for Republican and independent voters alike. The Consumer Price Index reading for September, released just days ago, showed core inflation accelerating at 6.6% year-on-year — the highest since 1982. That number should, by all traditional metrics, generate a decisive Republican wave.
Yet the correlation between economic disapproval and vote choice has frayed. Exit polling from the 2021 Virginia gubernatorial race and the 2022 special elections suggests that voters unhappy with the economy are not uniformly breaking for the GOP. The Dobbs decision, the January 6th Committee hearings, and concerns about election denialism have created a permission structure for suburban voters to stick with Democrats despite economic anxiety.
President Biden’s approval rating has ticked up from its summer nadir, settling in the low-to-mid 40s — still underwater, but no longer in the danger zone that typically presages a shellacking. The White House has leaned heavily on the Inflation Reduction Act, the CHIPS Act, and a declining uninsured rate to argue that governance is occurring. Whether that argument penetrates the final two weeks of saturation advertising remains the central uncertainty.
The Ground Game and the Early Vote
The final fifteen days are, operationally, the first fifteen days of voting.
In Pennsylvania, more than 500,000 mail ballots have already been requested; in Georgia, early in-person voting began this week with record-breaking first-day turnout. Democrats have historically dominated the early vote, building a cushion that Republicans must overcome on Election Day. But 2020 scrambled those patterns, and 2022 offers no reliable template. The RNC has invested heavily in “banking votes” — urging Republicans to vote early or by mail — a tactical shift from 2020’s rhetoric. Whether the base responds to the new messaging is a live question.
Turnout models are the subject of fierce debate in the war rooms of both parties. The “likely voter” screens used by public pollsters vary wildly, producing a spread of outcomes ranging from a Republican wave to a Democratic hold. The only certainty is that the electorate will be older, whiter, and more Republican than 2020 — but perhaps less so than 2014 or 2010.
Why it Matters
The composition of the 118th Congress will determine the legislative ceiling for the final two years of Biden’s first term, dictating whether the White House faces investigative oversight, legislative gridlock, or a functional — if fractious — partnership on must-pass legislation. A Republican House guarantees a blizzard of subpoenas targeting the administration; a Republican Senate would block judicial confirmations and complicate any Supreme Court vacancy. But a split outcome — a narrow GOP House and a Democratic Senate — would produce a distinct paralysis: enough power to investigate, insufficient power to legislate. For a global audience watching American governance, the next fortnight will set the parameters of Washington’s relevance for the next half-decade.