Britain’s energy security remains precariously dependent on a last‑minute arrangement with Belgium, masking deeper structural weaknesses in the country’s gas supply chain. The agreement, which will add roughly 10p to household bills each month, is presented as a modest insurance premium against a “low‑probability but high‑impact stress event”. Yet regulators and industry analysts warn that the pact does not address the fundamental challenges highlighted by the recent approval of the Jackdaw North Sea field and an impending warning from the National Energy System Operator about a potential 2030 supply crunch.
A precarious balance: the Belgium deal and its limits
The UK continues to import around 60 % of its gas, and even with the newly sanctioned Jackdaw development, the nation’s resilience remains fragile. To mitigate a possible outage of critical infrastructure—specifically the two LNG import terminals at Milford Haven—authorities have secured a maintenance contract with Interconnector Limited, the Belgian owner of the cross‑Channel pipeline. The cost, passed on to consumers, is modest: £1.19 per household annually. However, the arrangement is explicitly described by Ofgem as the “only currently available intervention” that can address immediate security of supply for the 2026/27 winter and provide benefits for the subsequent four years. In essence, it is a stop‑gap that buys time but does not resolve underlying vulnerabilities.
The deal’s scope is narrow. It merely ensures that compressors needed to pump large volumes of gas into Britain remain operational should the pipeline be called upon in an emergency. Without it, the Belgian operator had already signalled a reduction in capacity, reflecting the pipe’s underutilisation in recent years. While the financial impact on consumers is small, the broader implication is that the UK’s gas security is being managed through reactive, short‑term fixes rather than a coherent long‑term strategy.
Storage and terminals: the infrastructure gap
Britain’s current storage capacity is considered skimpy, a fact that amplifies the risk of supply disruption during peak demand periods. The government’s options are limited to a handful of potential projects:
* Centrica’s Rough facility in the North Sea is slated for closure next spring, removing a sizable storage asset unless the decision is reversed.
* The Bains development, championed by dCarbonX off the north‑west coast, could provide additional capacity, though its timeline remains uncertain.
* Onshore salt caverns are being explored as a more flexible storage solution, offering the possibility of rapid deployment.
* Forward‑purchase agreements on LNG, modelled on German practices, could diversify supply sources and reduce reliance on a single import route.
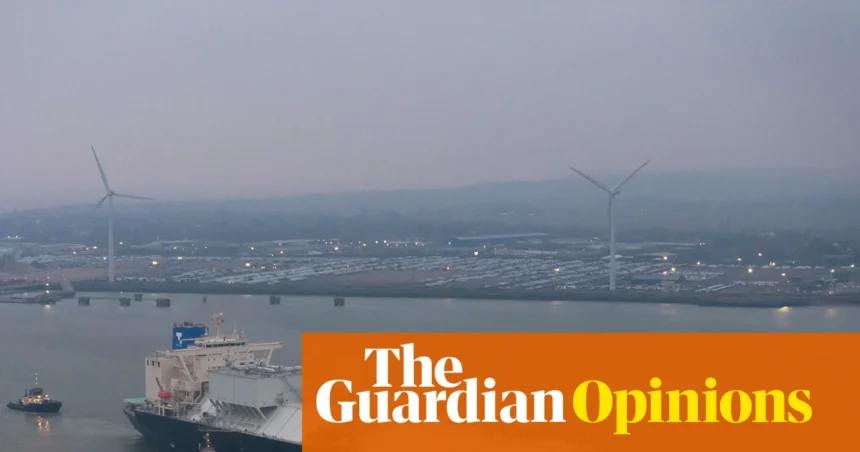
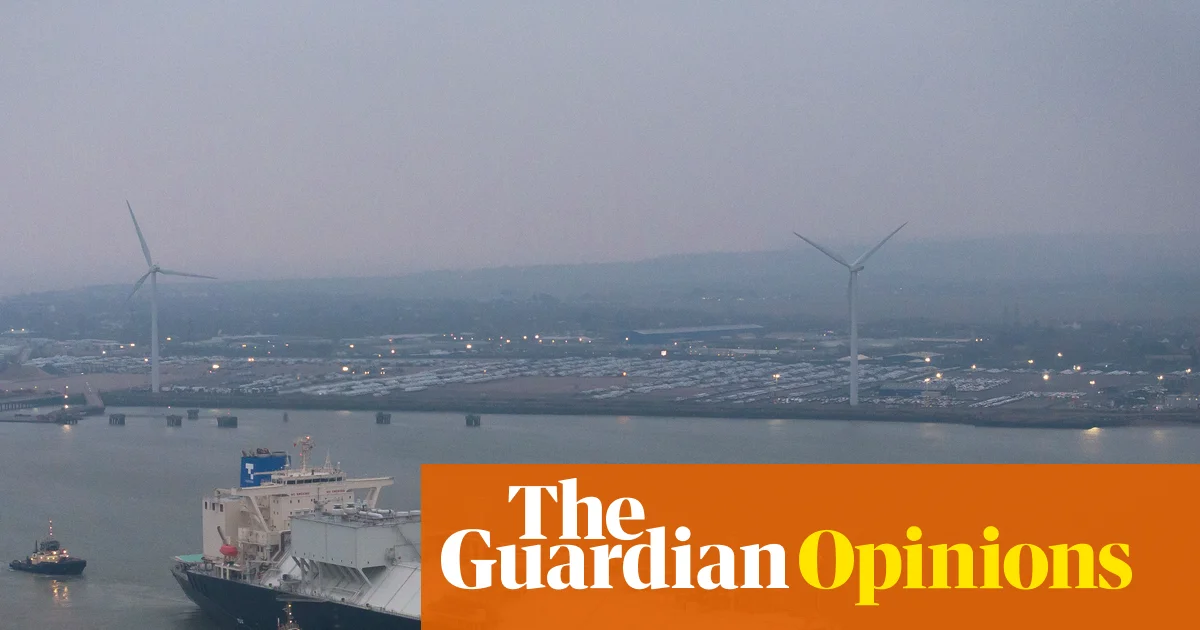
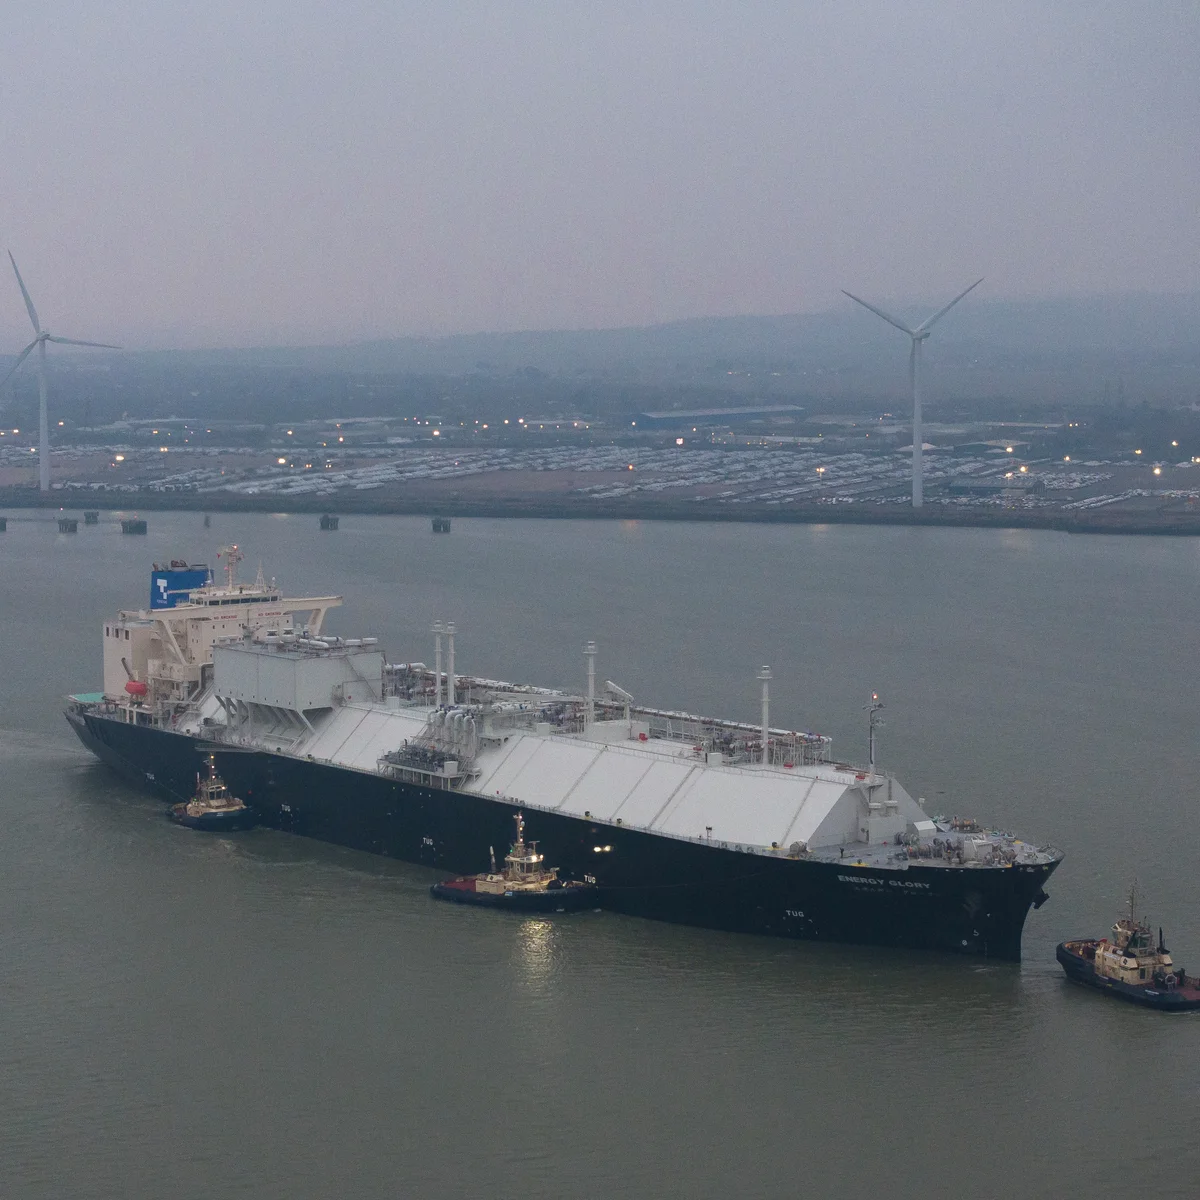
Beyond storage, the UK’s LNG import infrastructure is also under scrutiny. The Grain terminal east of London is already operational, but analysts argue that additional terminals may be required to meet growing demand, especially as renewable generation fluctuates and gas‑fired power stations remain a critical fallback. The existing terminals at Milford Haven, while vital, represent a single point of failure; any prolonged outage could expose the country to severe supply constraints.
Industry bodies, including National Gas, stress that “continued progress on government plans to reform security of supply arrangements will be vital to address enduring challenges in the years ahead”. The consensus is clear: without decisive investment in both storage and terminal capacity, the UK will remain exposed to seasonal spikes and potential geopolitical disruptions.
Government’s stalled response and the looming 2030 crunch
The urgency of the situation was underscored by a report from the National Energy System Operator (Neso) issued almost a year ago, which flagged an “emerging risk to gas supply security” by 2030. In response, the government pledged to “do whatever it takes” to avert a crisis. Yet, more than twelve months later, concrete action remains elusive.
An interim response to the Neso warning was delivered in August, but it failed to set a clear timetable for selecting necessary equipment or arrangements. The final, comprehensive response is not expected until next year, leaving a significant policy vacuum. This delay is particularly concerning given that infrastructure projects—whether storage sites or new LNG terminals—require years to develop and commission.
The government’s hesitation echoes its earlier indecision over the Jackdaw field, where prolonged deliberations nearly stalled a domestic source that could have reduced import reliance. Critics argue that the same protracted decision‑making process is now jeopardising efforts to bolster gas security. The Belgian deal, while providing temporary relief, is a reminder that the UK cannot rely on eleventh‑hour arrangements to safeguard its energy future.
What lies ahead for Britain’s gas security
Looking forward, the UK faces a stark choice: invest now in a diversified, resilient gas system or continue patching together short‑term solutions that leave the country exposed to future shocks. The path forward involves a multi‑pronged approach:
* Accelerating storage projects—whether through reviving Rough, fast‑tracking Bains, or expanding salt‑cavern capacity—will provide a buffer against peak demand.
* Expanding LNG import terminals will reduce dependence on a single import point and increase flexibility in sourcing.
* Developing forward‑purchase agreements can lock in supply at competitive rates, mitigating price volatility.
* Streamlining regulatory approvals for new energy infrastructure will shorten delivery timelines, ensuring that projects are ready before the anticipated 2030 pressure point.
Policy makers must also consider the role of gas‑fired generation in the transition to net‑zero. While renewable capacity grows, the intermittency of wind and solar means gas will remain a necessary hedge against supply gaps. Ensuring that this hedge is robust will require sustained investment and clear, long‑term planning.
The Belgian agreement is a prudent stop‑gap, but it should be viewed as a bridge to a more robust strategy. The window to act is narrowing, and the cost of inaction could be far higher than the modest monthly bill increase currently being imposed on households.
Why it Matters
The fragility of Britain’s gas supply chain has direct implications for household budgets, industrial productivity, and national security. A disruption during a cold snap could lead to power outages, economic losses, and social hardship. Moreover, the UK’s reliance on imported gas leaves it vulnerable to geopolitical shifts and market volatility. Investing in storage, terminals, and forward‑purchase mechanisms is not merely an energy policy issue; it is a fundamental component of economic stability and resilience. Failure to act decisively now could undermine the country’s transition to cleaner energy, leaving consumers exposed to price spikes and supply shortages at a time when the nation can least afford them.