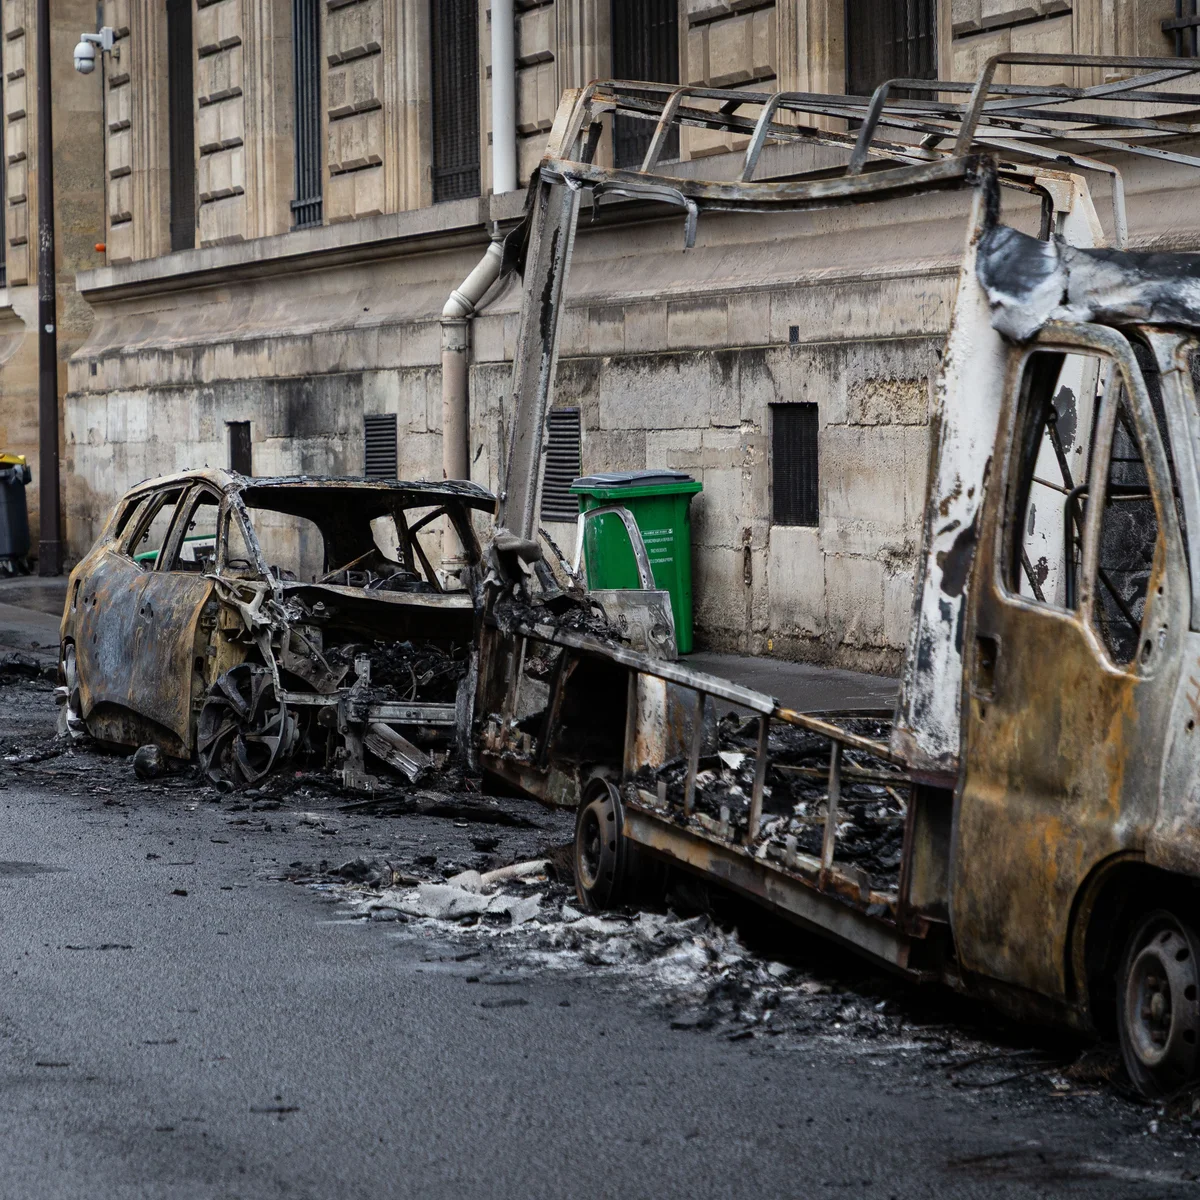
French government borrowing costs have vaulted above those of the United States for the first time in over a decade, a stark signal that investors are losing patience with Paris’s political paralysis. The yield on the benchmark 10-year OAT climbed to 5.089 per cent on Thursday, breaching the psychologically important 5 per cent barrier for the first time since 2002 and pushing the premium over German bunds to its widest in nearly 15 years. The sell-off comes as France grapples with a budget deficit of 5.1 per cent of GDP, a debt pile exceeding 115 per cent of economic output, and violent protests that have left city centres scarred and nearly 2,400 people in custody.
Protests and paralysis: a toxic mix for investors
What began as peaceful marches demanding more teachers and repairs for crumbling schools spiralled into widespread disorder over the weekend. In Paris, Bordeaux, Nice and Marseille, distinct groups broke away from the main demonstrations to clash with police, torch public buildings and loot thousands of shops. The interior ministry’s tally of nearly 2,400 arrests underscores the scale of the unrest, but the economic fallout may prove longer-lasting than the physical damage.
The violence has compounded a legislative deadlock that has paralysed President Emmanuel Macron’s reform agenda. Plans to raise the state pension age from 62 to 64 — a centrepiece of his effort to curb spending — remain stalled in parliament, alongside a broader package of fiscal tightening measures. Without a credible path to deficit reduction, the market is doing the work for policymakers, pricing in a risk premium that makes every euro of new borrowing more expensive.
Contagion fears spread across the eurozone
The turbulence is not contained to France. Jim Reid, a market strategist at Deutsche Bank, noted that the sell-off has begun to ripple across southern Europe. Italy’s 10-year spread over German bunds widened 3.8 basis points to 116, while Spain’s gap expanded 3.1 basis points to 66 — its widest level since June 2025. The mechanism is familiar: when the eurozone’s second-largest economy wobbles, investors reassess the risk of its neighbours, particularly those with their own elevated debt ratios.
This contagion dynamic complicates the European Central Bank’s calculus. Carsten Brzeski of ING argued that rising yields have effectively tightened financial conditions on the ECB’s behalf, reinforcing the case for a pause at next week’s rate-setting meeting. The bank lifted its key rate to 2.5 per cent in September; Brzeski expects officials to hold fire in October and push any further tightening to December — if the fiscal picture clarifies.
The ECB’s dilemma: fiscal dominance in real time
The current episode lays bare a tension that has haunted the eurozone since the sovereign debt crisis: monetary policy cannot substitute for fiscal discipline. As Brzeski put it, “bond markets have taken over the ECB’s role, making rate hikes less likely.” In other words, the market is delivering the tightening that the central bank might otherwise have engineered — but in a disorderly, unpredictable fashion that threatens financial stability rather than ensuring price stability.
For the ECB, the ideal outcome is a French budget that credibly narrows the deficit, allowing yields to settle and the bank to resume its own tightening cycle on its own terms. The alternative — prolonged political gridlock and a deepening sell-off — would force the central bank into a reactive posture, potentially requiring emergency interventions to prevent fragmentation in the sovereign bond market. Neither option is comfortable.
Why it Matters
France’s crossing of the 5 per cent yield threshold is more than a symbolic milestone; it marks the moment the market decided that political dysfunction carries a tangible price tag. For French households and businesses, higher sovereign yields transmit directly into costlier mortgages, pricier corporate loans and tighter credit conditions — a de facto austerity imposed not by parliament but by bond vigilantes. For the eurozone, the episode is a reminder that the currency union’s architecture remains incomplete: without a central fiscal capacity or enforceable discipline, the fate of the bloc’s second-largest economy still rests on the vagaries of national politics. If Paris cannot forge a consensus on pensions and spending, the bill will be paid in higher borrowing costs across the continent — and the ECB will be left cleaning up the mess.