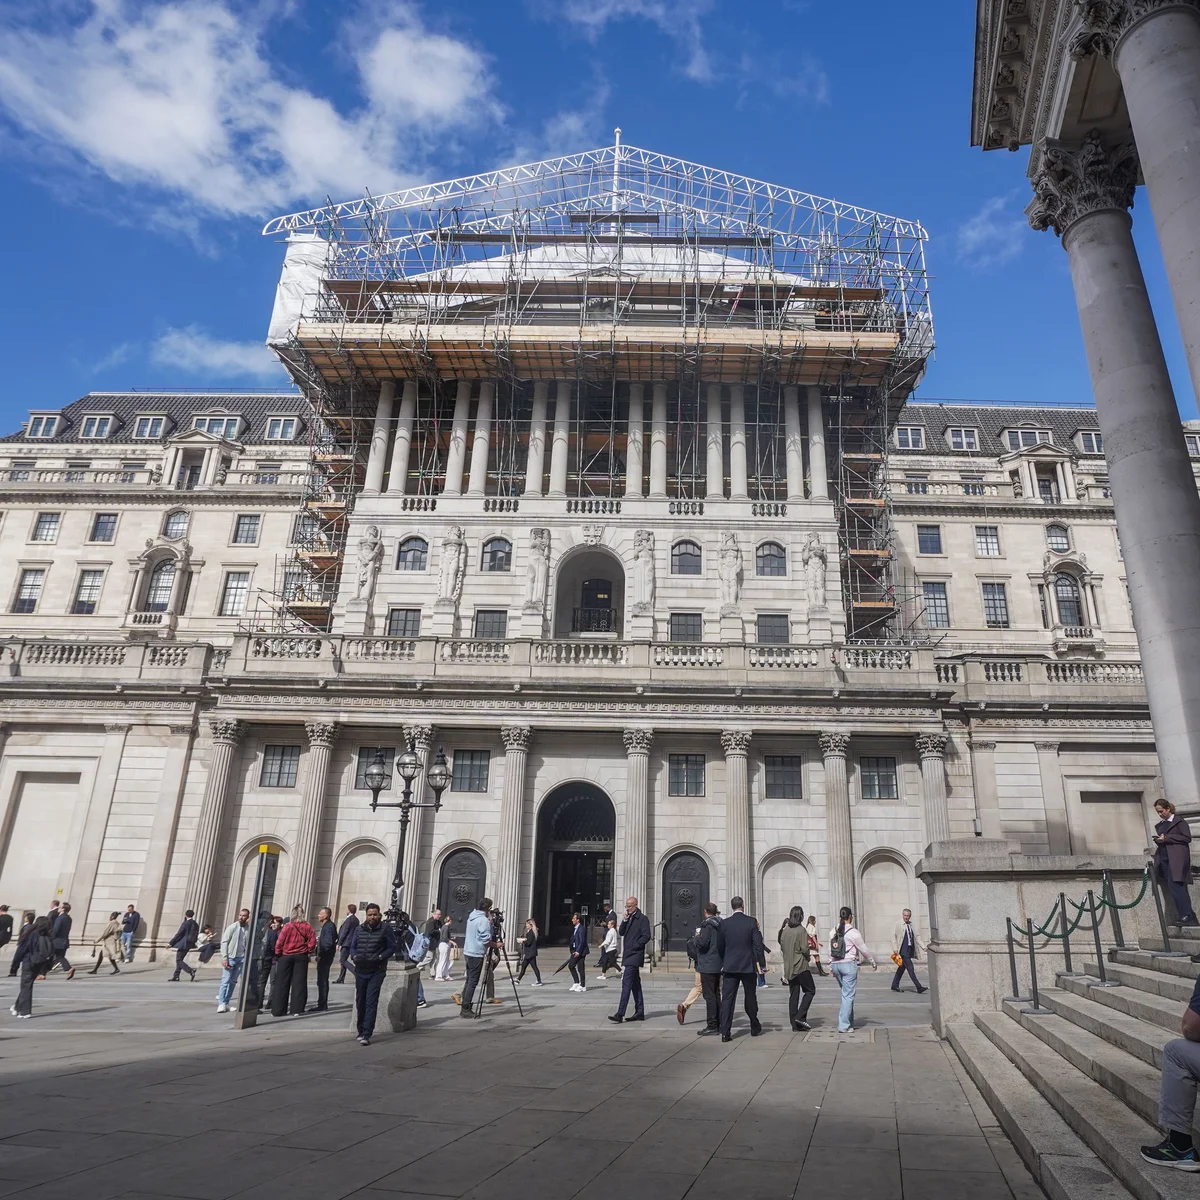
The Bank of England is widely expected to raise interest rates for the first time in nearly a year this week, a move that threatens to deepen a cost-of-living squeeze already bearing down on millions of British households. With inflation climbing to 3.5% in September — well above the 2% target — Threadneedle Street’s monetary policy committee (MPC) looks set to lift the base rate from 3.75% to 4% on Wednesday. Financial markets are pricing in as many as four quarter-point increases over the coming twelve months, a trajectory that would push borrowing costs to levels not seen since the aftermath of the mini-budget crisis.
A perfect storm for borrowers
The timing could hardly be worse for the 2.3 million households due to roll off fixed-rate mortgages in 2027. Data from UK Finance, the banking industry body, shows a further 700,000 borrowers are scheduled to refinance before the year is out. Many secured their current deals when rates were significantly lower; the average two-year fixed rate has already climbed above 5.5% in recent weeks, driven higher by volatility in the swap markets that underpin mortgage pricing.
Mortgage approvals fell to a near three-year low in September, according to figures released last week, as prospective buyers pulled back in the face of rising costs. The housing market, which had shown tentative signs of recovery earlier in the year, is now at risk of stalling completely.
Inflation driven by energy shock, not demand
The Bank’s hand has been forced by a supply-side shock rather than an overheating economy. Since the outbreak of war in the Middle East and the subsequent closure of the Strait of Hormuz, oil prices have remained stubbornly elevated. Ofgem’s energy price cap is forecast to jump by more than £400 in January, according to EDF’s latest projection, piling further pressure on household budgets.
This marks a dramatic reversal from the start of 2026, when the MPC was widely expected to cut rates several times as inflation drifted back toward target. Instead, the Bank has held fire since December 2025, adopting a wait-and-see stance that contrasted with the Federal Reserve, the European Central Bank and the Bank of Japan — all of which have already tightened policy this year.
Governor Andrew Bailey has made clear that the committee is watching closely for evidence of “second-round effects” — the point at which higher prices feed into wage demands, embedding inflation in the economy. So far, the labour market has remained relatively subdued, but officials are wary of declaring victory too soon.
Budget offers limited relief against a grim backdrop
Chancellor John Healey’s first budget attempted to cushion the blow. A £100 payment to 20 million households, the cancellation of planned fuel duty rises and an extension of the VAT cut on electricity bills form the centrepiece of a cost-of-living package funded by tax increases on banks, savers and landlords. Healey said the measures were designed to “take the pressure off in the coldest months and see people through to the spring.”
But the Office for Budget Responsibility (OBR) painted a stark picture alongside the fiscal statement. The watchdog now expects real household disposable incomes to fall by 0.6% next year — a swing of 1.2 percentage points from the 0.6% rise forecast in March. OBR member David Miles described the outlook as “a pretty grim picture.”
The UK economy outperformed expectations in the first half of 2026, emerging as the joint fastest-growing G7 nation, partly powered by AI-related sectors. Yet official forecasts for 2027 have been sharply downgraded as the drag from higher energy costs begins to weigh on activity. City economists are sceptical that the Bank will deliver the four rate rises priced into markets; most see two increases as the more likely scenario.
Why it Matters
The convergence of rising mortgage costs, soaring energy bills and falling real incomes creates a trifecta of pressure that will test the resilience of British households well into 2027. For the 2.3 million families facing remortgaging next year, the Bank’s decision this week is not an abstract macroeconomic event — it is a direct determinant of whether they can keep their homes, maintain their standard of living, or are forced into painful cutbacks. The government’s targeted support may soften the landing for some, but it does not alter the fundamental arithmetic: higher rates, higher bills and lower growth are now baked into the forecast. How the MPC navigates the coming months — and whether it can tame inflation without crushing the recovery — will define the economic landscape for a generation of borrowers.