The Reserve Bank of Australia is expected to deliver a fifth consecutive interest-rate increase on Tuesday, lifting the official cash rate to its highest point since 2008 and signalling that the nation’s economic expansion is set to lose further momentum. The move comes as policymakers intensify their battle against persistent inflation, with the global Middle East conflict and a deepening housing downturn adding layers of complexity to an already fragile outlook. Economists across the board have revised their forecasts downward, painting a picture of a economy that is growing below trend, facing mounting pressure on household budgets, and confronting a rising risk of recession.
RBA’s Fifth Hike and the 2008 Threshold
The decision due on Tuesday will mark the fifth rate increase in as many months, a pace that underscores the central bank’s determination to bring inflation back within target. The cash rate is set to surpass the level last seen in the aftermath of the global financial crisis, a threshold that carries psychological weight for mortgage holders and investors alike. In its latest guidance, the RBA has indicated that higher borrowing costs will need to be maintained for an extended period to ensure price stability, a stance that has been reinforced by recent comments from senior officials who have warned against premature easing. The market has priced in the hike with near-certainty, but the broader implication is that the cost of credit will remain a drag on consumption and investment throughout the year ahead.
Growth Forecasts Downgraded as Inflation Persists
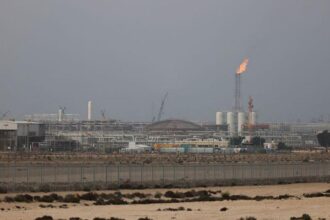
Major banks have swiftly updated their projections in response to the anticipated decision. Belinda Allen, head of Australian economics at Commonwealth Bank of Australia, downgraded her real GDP forecast to just 1 per cent by the middle of next year, nearly half the 1.8 per cent estimate published only a few months earlier. She noted that the extended geopolitical shock, particularly the ongoing Middle East conflict, has kept oil prices elevated far above previous expectations. Brent crude, the global benchmark, has climbed from about $US72 a barrel in early July to above $US110 in recent days as hopes for a swift peace settlement have faded. Allen had previously anticipated signs of recovery by the turn of the year, but now sees the economy “bottoming deeper and later,” with growth through 2027 projected at a modest 1.1 per cent.
Gareth Spence, head of Australian economics at National Australia Bank, echoed the dimmer trajectory, forecasting that the key jobless measure could climb from 4.7 per cent to as high as 5.4 per cent by the end of next year. He said this adjustment reflects recent rhetoric from RBA policymakers who are prioritising inflation control above all else. Spence also warned that the economy would grow below trend over 2027 and 2028, a view that aligns with the broader consensus that the post-pandemic expansion cycle is losing steam. Meanwhile, Treasury Minister Jim Chalmers last month cautioned that the December mid-year budget update would reveal a more pessimistic economic picture, a sentiment that has been validated by the stream of downgrades from the private sector.
Housing Market Correction and the Wealth Effect
The deteriorating outlook is being compounded by a property sector that continues to struggle. Shane Oliver, chief economist at AMP, noted that home prices could fall by as much as 15 per cent before levelling off late next year, with Sydney values already down 10 per cent from their recent peak. Drawing on RBA research, Oliver explained that such a correction would trigger a significant “wealth effect,” prompting worried homeowners to pull back on spending and further cool demand. A weakening market will also weigh on homebuilding activity, adding another layer of pressure to an economy already grappling with multiple headwinds. While Oliver did not call an economic contraction his base case, he warned there was a “significant and rising” risk of recession, the probability of which could reach as high as 45 per cent should the RBA proceed with the expected hike on Tuesday. “We don’t know the tipping point,” he said, highlighting the uncertainty that surrounds the turning point where tighter policy tips the broader economy into decline.
Labour Market, Unemployment and Recession Risks
The labour market is feeling the squeeze as the RBA’s tightening cycle bites. NAB’s Spence suggested that unemployment may need to rise higher than previously thought to bring inflation sustainably under control, a trade-off that has become increasingly familiar in central bank playbooks across the world. The CBA, meanwhile, sees the jobless rate peaking at 5.1 per cent over a similar horizon, reflecting a slightly more optimistic – though still concerning – read on labour dynamics. Either scenario points to a labour market that is softening, with fewer job openings and slower wage growth than seen during the post-COVID rebound. As union leaders protested against the anticipated rate hike in front of the RBA’s Sydney offices on Monday morning, the message was clear: the central bank’s multi-year strategy of taming inflation without sacrificing the employment gains of the post-pandemic era now looks increasingly unlikely to succeed.
Why it Matters
The RBA’s fifth rate increase in as many months represents more than a routine policy adjustment; it is a decisive signal that the central bank is willing to accept slower growth and higher unemployment in exchange for bringing inflation back within target. With the cash rate climbing to its highest level since 2008, Australian households are facing the sharpest borrowing costs in nearly two decades, at a time when real wages are already stretched and the housing market is correcting sharply. The confluence of elevated oil prices, a deepening property downturn, and downward-revised growth forecasts points to an economy that is losing momentum across multiple fronts. For policymakers, the challenge is to navigate a path that curbs price pressures without tipping the country into a prolonged downturn – a balancing act that has grown increasingly precarious with each successive hike.