The cost of borrowing in the United States has surged to its highest point in nearly two decades. With the 10-year Treasury yield breaking through the 5% barrier, American households are bracing for a significant shift in their financial landscapes. This milestone, last seen in 2007, signals a new era of economic pressure for consumers across the nation.
The Surge in Government Borrowing Costs
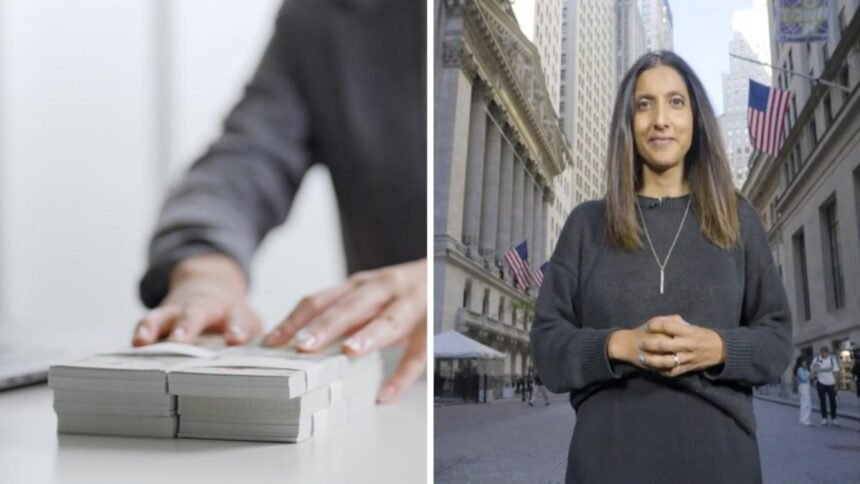
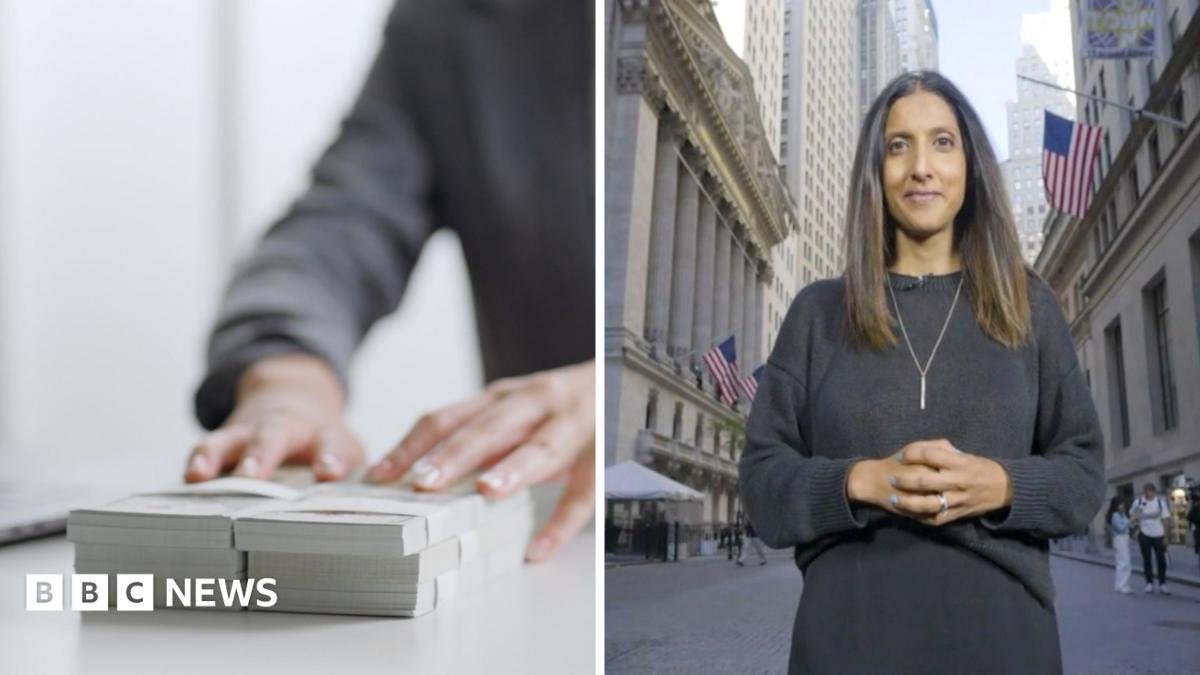
The 10-year Treasury yield acts as the benchmark for the global financial system. When this metric climbs, it sends shockwaves through the broader economy. The recent crossing of the 5% threshold is a stark reminder of the shifting tides in monetary policy. As the Federal Reserve maintains its aggressive stance against inflation, investors are demanding higher returns on government debt. Consequently, the cost of funding the national deficit has escalated dramatically. The BBC’s Samira Hussain recently highlighted this phenomenon, explaining how the mechanics of bond markets directly dictate the terms of everyday credit.
This is not merely a statistic for Wall Street traders; it is the foundation upon which consumer interest rates are built.
The Ripple Effect on Household Finances
For the average American consumer, the implications are immediate and often painful. Mortgage rates are the first to feel the squeeze, tracking closely alongside the 10-year yield. Prospective homebuyers are now facing the steepest borrowing costs in a generation, pushing the dream of homeownership further out of reach. Similarly, auto loans and credit card interest rates are climbing, leaving households with less disposable income each month. The strain on family budgets is undeniable. When the cost of carrying debt rises, discretionary spending inevitably falls. Retailers and service providers are already noting the cooling effect on consumer demand, a trend that could shape the economic outlook for the remainder of the year.
The pressure on family budgets is undeniable.
Navigating the New Economic Reality
Yet, it is not all doom and gloom for those with cash reserves. Higher yields also mean better returns on savings accounts and certificates of deposit. Savers are finally seeing a decent return on their deposits after years of negligible interest. This creates a bifurcated landscape: debtors are punished, while savers are rewarded. Financial advisors are urging consumers to organise their portfolios and lock in fixed rates where possible. Refinancing existing debt or consolidating high-interest credit cards could provide a crucial buffer against the rising cost of living. As the economic centre shifts, adaptability will be the key to financial resilience.
Adaptability will be the key to financial resilience.
Why it Matters
Understanding this shift is crucial because it defines the boundary between economic stability and hardship for millions. The return to 5% yields marks the end of an era of cheap money, fundamentally altering how Americans spend, save, and invest. As the financial landscape tightens, the pressure on policymakers to balance inflation control with consumer welfare will intensify. The choices made in the coming months will determine whether this transition is a temporary squeeze or a long-term structural change for the American economy.