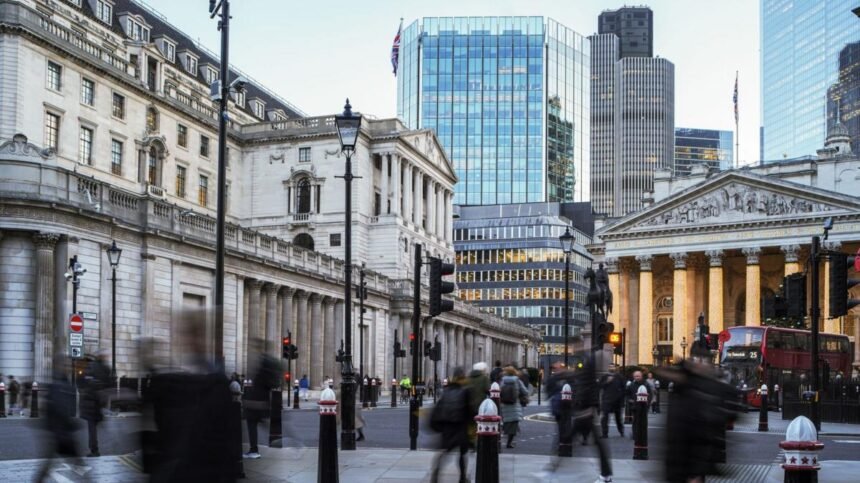
Policymakers at the Bank of England are expected to lift the benchmark rate on Thursday, marking the first increase in more than three years. Most analysts anticipate a modest quarter‑point rise from 3.75 % to 4 %, a move that would raise borrowing costs for households and businesses while offering modest gains for savers. The decision comes as inflation, driven largely by petrol, diesel and energy prices linked to ongoing geopolitical tensions, remains above the Bank’s 2 % target. The Monetary Policy Committee (MPC) has kept rates unchanged at its last six meetings, but rising price pressures and a fragile growth outlook are now prompting a shift in policy stance. The announcement will be made at 12:00 GMT, and markets will be watching closely for any forward guidance on future moves.
Impact on borrowers and savers
The Bank’s base rate influences the price of mortgages, credit cards and other loans, as well as the interest paid on savings accounts. A rise would have an immediate effect on the roughly 510,000 households with tracker mortgages, whose repayments would climb by about £31 per month for a typical loan, according to UK Finance. Those on variable‑rate deals—around 470,000 borrowers—would face a smaller immediate increase, typically £14 a month, but would need to wait for their lenders to adjust terms. Fixed‑rate borrowers, while insulated from instant changes, will see their future deals priced higher, as lenders have already incorporated the anticipated rise into new product rates.
Savers, on the other hand, may begin to see improved returns as banks pass on the higher base rate to deposit accounts. However, the benefit is likely to be modest, and the overall impact will depend on how quickly banks update their offering. The diverging effects mean that many households are now weighing the trade‑off between the security of a fixed rate and the potential savings of a tracker, especially as the Bank prepares to tighten monetary policy for the first time in a long period.
Mortgage market reactions
Data from financial information service Moneyfacts shows that, as of 4 November, the average two‑year fixed residential mortgage rate stood at 5.96 %, while the average five‑year fixed rate was 5.99 %. These figures are significantly higher than the levels seen in 2021, when the average five‑year fixed remortgage rate among the ten largest lenders was just 1.30 %. Broker L&C estimates that borrowers rolling off a five‑year deal today could face almost £5,000 more in annual repayments on a £200,000 loan over a 25‑year term compared with those who secured a remortgage in 2021.
The surge in fixed rates has prompted a renewed interest in tracker mortgages, as some borrowers hope to lock in lower costs now, even if they accept the risk of future rises. “The right choice ultimately depends on borrowers being confident they can stomach future rises. The devil is in the detail,” said Rachel Springall from Moneyfacts. Financial advisers stress that the decision hinges on individual circumstances, risk tolerance and the ability to absorb higher payments should the Bank continue to tighten policy.
Broader economic considerations
Inflation, measured by the Consumer Prices Index, stood at 3.5 % in the year to September 2026, up from 3.1 % the previous month and well above the Bank’s 2 % target. While this is far below the peaks recorded a few years ago, the upward trend is being fuelled by higher fuel costs, the lingering effects of the Iran conflict on global energy markets, and an anticipated surge in domestic energy prices next January. The Bank’s Monetary Policy Committee must balance these price pressures against a weakening growth outlook, as recent data suggests the UK economy is slowing.
“A quarter‑point rise is already widely expected, but the Bank now has to balance inflation that is still too high against an economy where the growth outlook has weakened sharply,” said Chris Cheverall, head of UK at trading platform CMC Markets. “The decision is increasingly less about whether rates reach 4 % and more about what follows after that.” The MPC’s forward guidance will be scrutinised for clues on whether further hikes are likely, or if the policy stance will shift to a more neutral position as inflationary pressures begin to ease.
The broader implications extend beyond mortgage holders. Higher rates will affect corporate borrowing, potentially dampening investment and hiring, while also encouraging saving. International events, particularly the ongoing war and its impact on energy supplies, continue to shape the UK’s economic trajectory, making the Bank’s policy decisions a focal point for both domestic and global markets.
Why it Matters
The Bank of England’s first rate rise in over three years marks a pivotal moment for the UK’s financial landscape. For millions of households, the change will directly affect monthly budgets through higher mortgage repayments, while also offering modest improvements for savers. The move reflects a delicate balancing act between curbing inflation—currently above target and driven by energy and fuel costs—and supporting an economy that shows signs of slowing. As borrowers and lenders alike adjust to the new environment, the decisions made this week will set the tone for credit availability, housing affordability and broader economic confidence in the months ahead. The repercussions will be felt not only in British living rooms but also across global markets that watch the UK’s monetary policy as a barometer of Western economic resilience.