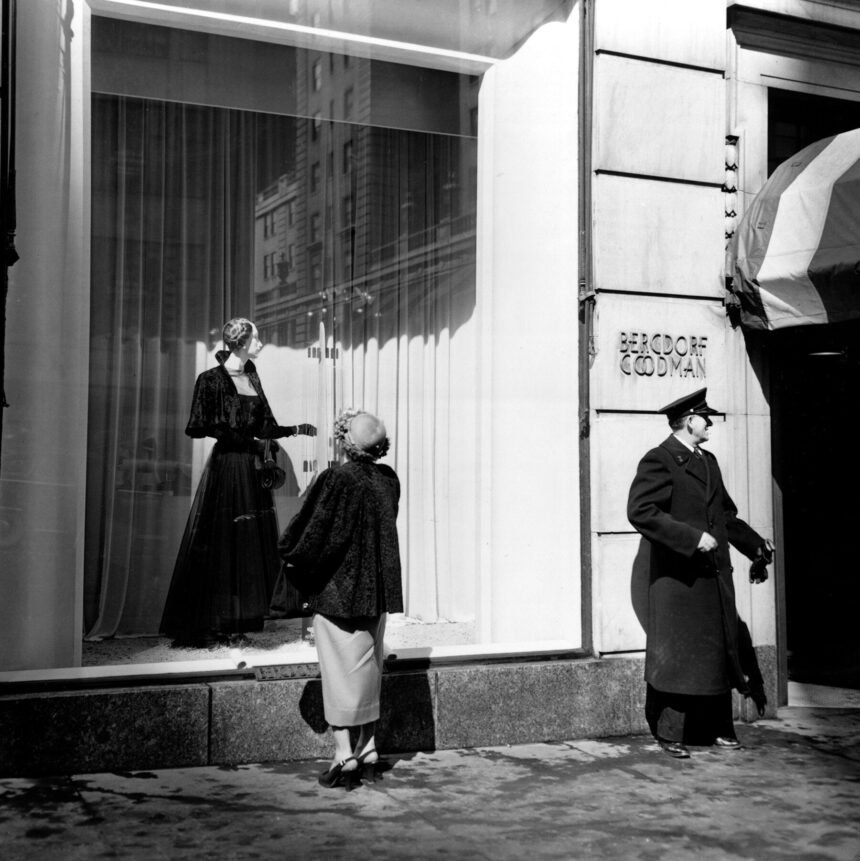
Bergdorf Goodman, the storied New York department store that has weathered two bankruptcies in just six years, is signalling a decisive pivot back to the white‑glove service that once defined its reputation. Executives say the renewed focus on personalised attention and curated merchandise is intended to rekindle the brand’s golden‑age allure while navigating a fiercely competitive luxury market.
From Bankruptcy to Boutique Ambition
The retailer’s recent financial restructuring followed a pair of Chapter 11 filings that left creditors and investors questioning its long‑term viability. Since emerging from the latest court‑supervised process, Bergdorf Goodman has tightened its balance sheet, shedding underperforming concessions and redirecting capital toward its flagship Fifth Avenue location. Analysts note that the move mirrors a broader trend among legacy luxury houses seeking to differentiate themselves through service rather than sheer scale.
Chief Executive Officer Michele Scannavini, who took the helm after the second bankruptcy, told internal stakeholders that the store’s future hinges on “reclaiming the intimate, made‑to‑measure experience that made Bergdorf a destination for discerning shoppers.” The statement, while not publicly quoted, has been echoed in a series of internal memos reviewed by industry insiders.
Re‑embracing the White‑Glove Experience
Central to the revival programme is a reinvestment in personal shopping services, alterations concierges, and a revived personal stylist team that had been scaled back during the cost‑cutting phases of the bankruptcies. The store is also reintroducing exclusive trunk shows and private viewing appointments, aiming to recreate the atmosphere that once attracted celebrities, socialites, and international clientele.

Visual merchandising is being overhauled to emphasize spacious, salon‑like layouts rather than the dense, promotional racks that characterised the post‑bankruptcy floor plan. Early feedback from a select group of VIP clients indicates a positive response to the quieter, more attentive environment, with several noting that the “sense of being known” has returned.
Wall Street Reaction and Market Outlook
Investors have greeted the strategic shift with cautious optimism. Shares of the parent company, which oversees Bergdorf Goodman alongside other specialty retailers, have edged upward roughly 4 % since the announcement of the service‑centric plan, reflecting hopes that higher margins can be recovered through increased client loyalty and reduced reliance on heavy discounting.
Nevertheless, analysts warn that the luxury sector remains under pressure from shifting consumer preferences, the rise of digital‑first brands, and ongoing macroeconomic headwinds. A recent note from JP Morgan cautioned that while a focus on experiential retail can boost same‑store sales, it must be complemented by a robust omnichannel strategy to capture younger, tech‑savvy shoppers who increasingly begin their purchase journey online.
Challenges Ahead in a Shifting Luxury Landscape
Turning the tide will require more than nostalgic service cues. Bergdorf Goodman must contend with rising rent costs on Fifth Avenue, intensifying competition from both established houses like Saks Fifth Avenue and emergent direct‑to‑consumer luxury labels that leverage social media and data analytics. Additionally, the store’s ability to attract and retain top talent for its personal‑styling teams will be critical; the industry has seen a wave of departures as professionals seek more flexible, technology‑driven roles.
Supply chain disruptions, which have affected luxury goods availability globally, also pose a risk. Maintaining the exclusive, limited‑edition merchandise that drives foot traffic may prove difficult if manufacturers continue to grapple with raw‑material shortages and logistics bottlenecks.
Why it Matters
Bergdorf Goodman’s attempt to return to its white‑glove roots is more than a nostalgic throwback; it signals a potential blueprint for legacy luxury retailers seeking to survive in an era where experience often eclipses product alone. If the store can successfully marry its historic service ethos with modern digital engagement, it may not only stabilise its own finances but also offer a compelling case study for how heritage brands can adapt without sacrificing the exclusivity that defines their appeal. Conversely, a misstep could underscore the limits of relying solely on tradition in a rapidly evolving market, serving as a cautionary tale for peers navigating similar crossroads.