
Canada’s Prime Minister Mark Carney has delivered one of the fastest trade negotiations in modern diplomatic history, sealing a Comprehensive Economic Partnership Agreement with the United Arab Emirates in just 47 days — a sprint that signals his government’s determination to court Gulf capital as a cornerstone of Canada’s economic future. The deal, signed on July 24 in Toronto, was accompanied by a commitment of US$50-billion in Emirati investment and sets the stage for a high-stakes investment summit in the coming weeks that could reshape the flow of sovereign wealth into Canadian infrastructure, resources and industry.
The 47-Day Sprint That Surprised Even the Emiratis
There was a competitiveness baked into the negotiations from the outset. When Canada and the UAE agreed in November 2025 to pursue a trade agreement, Emirati President Sheikh Mohamed bin Zayed Al Nahyan referenced his country’s record-breaking deal with India. Canadian negotiators took the hint and bet they could do better.
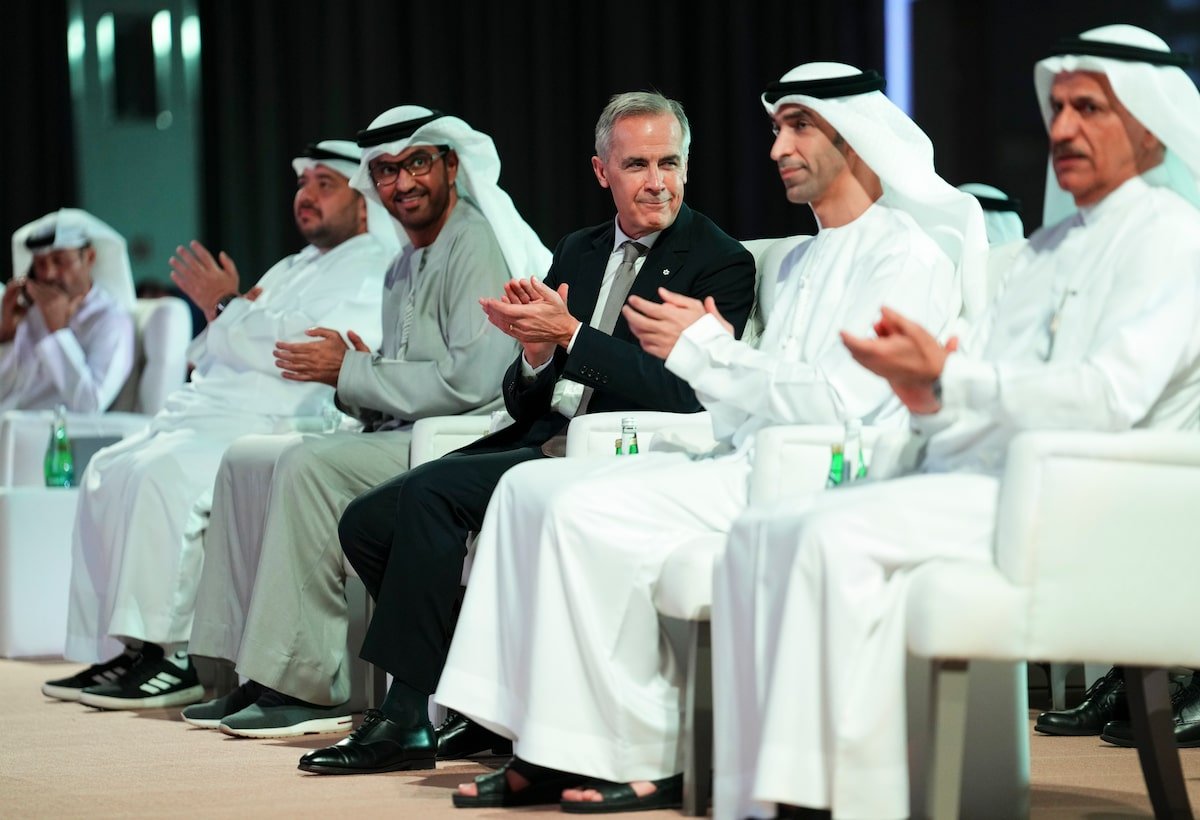
Prime Minister Carney set an uncompromising deadline: from the opening of talks to the signing ceremony, just 47 days. Trade Minister Maninder Sidhu played host to his Emirati counterpart, Dr. Thani bin Ahmed Al Zeyoudi, in Toronto during the final stretch of negotiations. When the ink was dry, both ministers claimed the speed as a personal triumph — the fastest negotiation either side had ever managed.
The velocity was not born of simplicity. The agreement, while significant, was neither the largest nor the most technically demanding deal on either country’s docket. The pace was, instead, a deliberate statement of intent. Ottawa wanted the Gulf to understand that Canada was no longer content to treat the region as an afterthought.
Billions on the Table: The Investment Summit That Could Change Everything
The real test of Carney’s Gulf strategy arrives next month. On September 14 and 15, Toronto will play host to the Canada Investment Summit, where the Prime Minister will personally lead a pitch to attract massive pools of Gulf capital into Canadian projects. The guest list reads like a who’s who of sovereign wealth: the UAE’s US$1.2-trillion Abu Dhabi Investment Authority, Investment Corporation of Dubai, ADQ and Mubadala Investment Co. — each managing hundreds of billions in assets — are all confirmed attendees.

Already, the financial commitments are substantial. XRG, the foreign-investment arm of Abu Dhabi National Oil Company, has been actively exploring an investment in LNG Canada Phase 2, the expansion of the liquid-natural gas export terminal in Kitimat, British Columbia. Gulf sovereign wealth funds collectively hold US$5.6-trillion in assets globally, according to Diego López, managing director of fund tracker Global SWF. Yet the flow of those funds into Canada over the past five years totalled just US$6.2-billion — a figure López describes as “still very insignificant when it comes to the size of the Canadian economy and potential.”
The prospectus for Carney’s summit highlights more than 160 projects open for investment, spanning infrastructure, critical minerals, clean energy and advanced manufacturing. The message is unmistakable: Canada is open for business, and it is looking to the Gulf first among its new partners.
From Chill to Courtship: How Carney Rewired Canada’s Gulf Strategy
Europe remains Carney’s headline priority in his campaign to diversify Canada’s trade relationships away from an increasingly unpredictable United States. But the Gulf has ranked a close second, pursued with a quiet intensity that has surprised long-time observers of Canadian foreign policy.
Arif Lalani, a former Canadian ambassador to the UAE and now a senior adviser at government relations firm StrategyCorp, put it plainly: “I think it’s long overdue that the Canadian government gives the Gulf region this level of priority. All of our European and other allies have made the Gulf a priority for decades.”
The catch-up, according to government and business sources familiar with the effort, has been an 18-month pursuit. Carney made personal trips to the UAE, Saudi Arabia and Qatar — a triangle of wealth that had not hosted a Canadian prime minister in decades. Cabinet ministers followed. A senior prime ministerial aide shuttled relentlessly between Ottawa and the Gulf. And Carney himself brought personal relationships forged over years in finance and climate policy to the table.
Before assuming office, Carney was already a familiar figure in Gulf circles. As governor of the Bank of England, he met Saudi finance ministers and central bank governors. As the UN’s envoy for climate action and finance, he attended COP28 in Dubai in 2023. And through his tenure at Brookfield Asset Management, he struck deals with Gulf sovereign wealth funds. In office, he texted directly with Sultan Al Jaber, chief executive of ADNOC and chairman of XRG and Masdar — the two had previously worked together when Al Jaber chaired COP28, where the UAE launched the Alterra energy-transition fund with a US$1-billion commitment to Brookfield’s Catalytic Transition Fund.
The diplomatic reset has not been without friction. In 2018, then-foreign affairs minister Chrystia Freeland’s public call for Saudi Arabia to release women’s rights activists triggered a five-year chill in relations. Carney has adopted a markedly different approach. After meeting Saudi Crown Prince Mohammed bin Salman in Jeddah in July, the Prime Minister insisted that “lecturing countries from afar is an ineffective strategy.” Critics have accused him of subordinating values to economic interests. His supporters argue he is simply practising a harder-headed form of statecraft — compartmentalising disagreements from interests and resolving them behind closed doors.
Beyond Trade: Defence, AI and the Architecture of a New Partnership
The agreements Carney’s government has signed with Gulf nations extend well beyond commerce. Canada posted a defence attaché to Qatar and signed a public safety co-operation agreement. Qatari paramilitary forces brought armoured vehicles to Vancouver ahead of a Qatar-Canada World Cup match, training alongside the RCMP. In Saudi Arabia, Ottawa signed a memorandum of understanding on artificial intelligence collaboration and pledged to lead a delegation of Canada’s “Maple 8” pension funds to explore investment opportunities there.
Artificial Intelligence Minister Evan Solomon visited the UAE. Sidhu and Defence Minister David McGuinty followed. Scott Gilmore, Carney’s then-foreign policy adviser and now principal secretary, served as the Prime Minister’s envoy, shuttling regularly to the Gulf. He was photographed by Gulf state media meeting senior figures in Doha in August, October and December 2025; in the UAE in October 2025 and April 2026; and in Oman in April — a relentless presence that, in a region where relationships carry enormous weight, opened doors at the highest levels.
The investment protection agreement with the UAE, which had languished with stops and starts since 2014, was finally signed in July. It was part of a broader recalibration: Canada’s internal national-security strategy, assembled soon after Carney took power, revolved around diversifying trade, strengthening the domestic economy and attracting foreign investment, with relationships outside North America reordered to place the Gulf second only to Europe.
The Saudi Angle and the Road Ahead
Saudi Arabia presents a different dynamic. Its investment strategy is tightly aligned with Vision 2030, the kingdom’s blueprint for economic transformation, which includes developing mineral wealth and establishing auto and aerospace industries. The Saudis are seeking two-way investment that builds domestic expertise, particularly in mining.
“Canada is number one in the Saudis’ mind when it comes to minerals,” said Jeffrey Steiner, chair of the Canada-Saudi Arabia Business Council. The Saudis have already invested indirectly in Canadian mining: their Manara Minerals Investment Company paid US$2.5-billion to Brazil’s Vale S.A. for a 10-per-cent stake in subsidiary Vale Base Metals, which produces nickel, copper and cobalt at operations in Sudbury, Voisey’s Bay and Thompson, Manitoba.
Finance Minister François-Philippe Champagne will lead a delegation of Canada’s Maple 8 pension funds to Saudi Arabia in November, signalling that the pipeline of two-way investment is only beginning to flow.
The Saudis, in particular, do not want to be seen as an ATM machine, Steiner noted. Qatar’s Prime Minister Sheikh Mohammed bin Abdulrahman bin Jassim Al Thani framed the Gulf’s investment philosophy as a survival strategy, recalling how Qatar’s pearl-diving economy collapsed around 1930 with the advent of cultured pearls. The Qatar Investment Authority, he said, is insurance against another collapse — and a tool to build global companies so that Qatar’s economy is not “capped” by the country’s small size.
Why it Matters
Carney’s Gulf strategy represents a fundamental reorientation of Canadian foreign policy, one that prioritises economic security and strategic autonomy over the traditional emphasis on values-based diplomacy. The 47-day trade deal with the UAE is not merely a commercial agreement — it is a signal to the world that Canada is willing to move quickly, think differently and engage pragmatically with regions it once neglected. With Gulf sovereign wealth funds controlling trillions in assets and Canada facing an uncertain trade future under sustained American pressure, the stakes could not be higher. The September summit will provide the first real measure of whether Carney’s courtship translates into concrete capital, and whether Canada can convert diplomatic warmth into the kind of long-term investment that reshapes an economy. The next chapter of Canadian prosperity may well be written in Abu Dhabi, Riyadh and Doha.