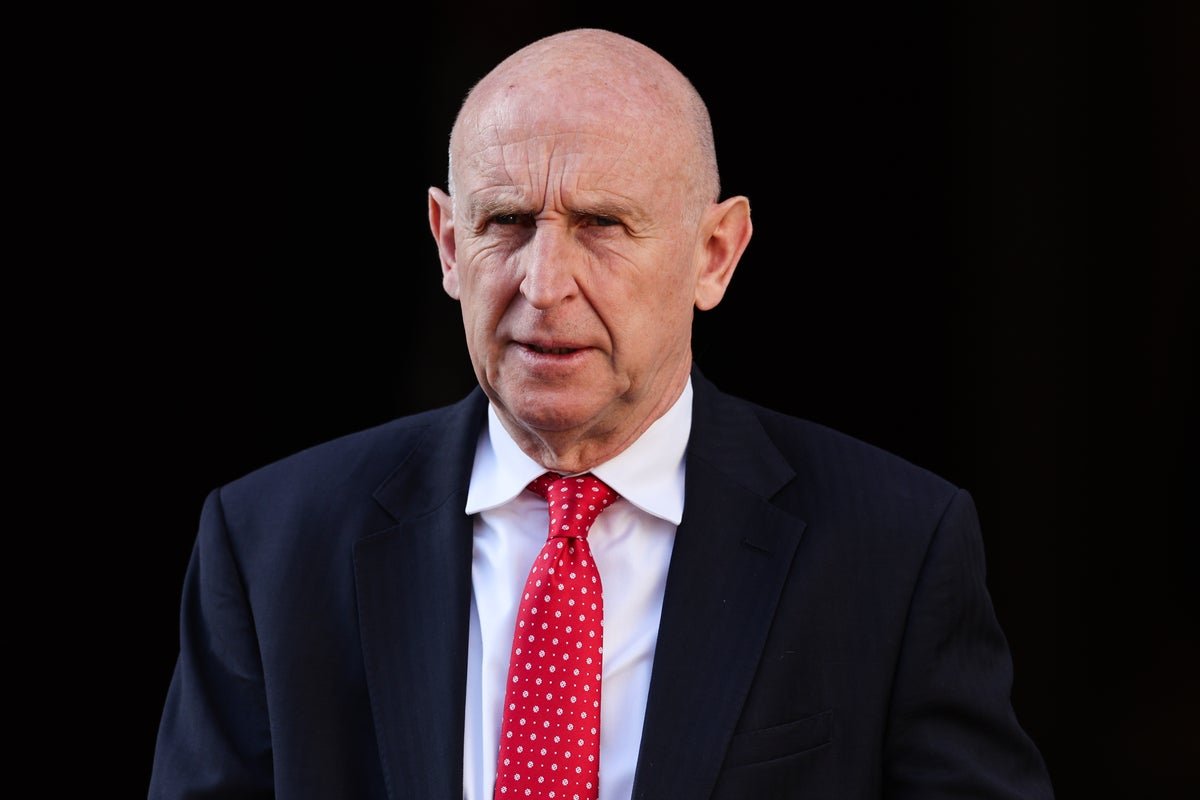
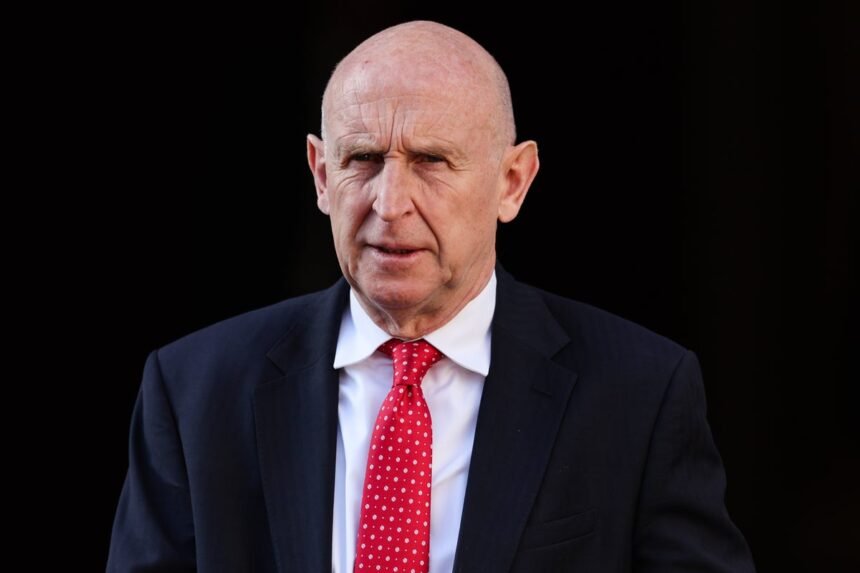
Chancellor John Healey is facing mounting pressure to consider tax increases or spending cuts in his first Budget, as a stark new assessment reveals the Government’s fiscal cushion has shrunk by nearly £12 billion. The dramatic erosion, attributed to elevated borrowing costs stemming from the Iran conflict and a sluggish growth outlook, leaves Mr Healey with what advisers are describing as severely constrained options when he delivers his Autumn Budget on 28 October.
A Dramatic Decline in Fiscal Room
The findings, drawn from KPMG’s latest economic outlook, paint a sobering picture of the public finances. Fiscal headroom — the buffer the Government maintains against its own fiscal rules — has fallen from £23.6 billion projected earlier this year to approximately £12 billion, a reduction of almost half.
KPMG attributes roughly £9 billion of that loss to surging long-term borrowing costs on UK government debt, triggered by a gilt sell-off linked to inflation concerns arising from the Middle East conflict. A further £2 billion erosion is expected as a result of anaemic economic growth and anticipated downgrades from the Office for Budget Responsibility.
The Chancellor acknowledged the difficulties, noting that Britain’s growth trajectory “has been weak.” Speaking publicly on the matter, Mr Healey indicated awareness that there is “little room for manoeuvre” heading into his inaugural Budget statement.
The Government has pledged not to raise taxes on working people, which narrows the options further. KPMG warned that restoring headroom to its previously projected levels would likely require either tax rises on other fronts or meaningful reductions in public spending — a politically delicate balancing act for a Chancellor who entered office only in July, appointed by Prime Minister Andy Burnham.
Inflation and Interest Rates Set to Climb
The economic forecast contained in KPMG’s report adds further complexity to Mr Healey’s calculations. UK interest rates are expected to rise from their current level of 3.75% to 4% by November, the analysis predicts. They may begin to ease again next summer as the influence of energy prices on inflation starts to fade.
Inflation, which currently stands at 3.1% as of August, is forecast to climb to around 3.5% through the autumn months before peaking at approximately 4% in the first quarter of next year. Those rising prices are expected to weigh heavily on household budgets and dampen consumer confidence.
Overall economic growth is projected at 1.3% for 2026, with activity slowing noticeably in the final six months of the year as inflationary pressures erode spending power. Growth is then anticipated to edge up modestly to 1.4% in 2027.
The convergence of higher borrowing costs and weakening growth creates a challenging backdrop for any Chancellor. KPMG was unequivocal in its assessment, stating that the Chancellor “will have limited scope to provide significant support for growth or the cost of living” when the Budget is delivered next month.
Political Implications of a Constrained Budget
Mr Healey’s October statement will be his first Budget since taking charge of the Treasury. He inherited a set of public finances considerably more fragile than those outlined just months earlier, and the political expectations placed upon him remain high.
With the Labour Government keen to demonstrate fiscal responsibility while also addressing public dissatisfaction over living costs, the pressure on October 28 is considerable. Any decision to tighten spending or introduce new tax measures carries the risk of alienating voters, yet doing nothing risks further erosion of credibility in the Government’s economic management.
The OBR’s expected downgrades will add an unwelcome layer of scrutiny when the Office publishes its own forecasts. Opposition parties are almost certain to seize on the narrowing gap between projections and reality to challenge the Chancellor’s authority on economic affairs.
KPMG’s analysis makes clear that the constraints are not merely temporary. The combination of geopolitical instability driving gilt yields higher and domestic growth failing to gather pace means that Mr Healey faces a prolonged period of fiscal constraint rather than a single difficult Budget cycle.
The question is not simply whether the Chancellor can deliver a credible Budget on 28 October, but whether the measures he announces will be sufficient to restore confidence in the Government’s financial planning at a time when households are already feeling the squeeze.
Why it Matters
The halving of the Government’s fiscal headroom has far-reaching implications for households and businesses across the country. Every pound of reduced buffer limits the Chancellor’s ability to cushion the cost of living crisis, invest in public services, or stimulate economic growth at a time when inflation is accelerating and household spending is under pressure. For ordinary families, this means the Budget announced later this month is unlikely to deliver meaningful relief — and could well bring announcements that directly affect their finances. The decisions Mr Healey makes in the coming weeks will shape the economic trajectory of the country for years to come, and the narrow path he must walk leaves little margin for error.