The Moneris Sale Announcement
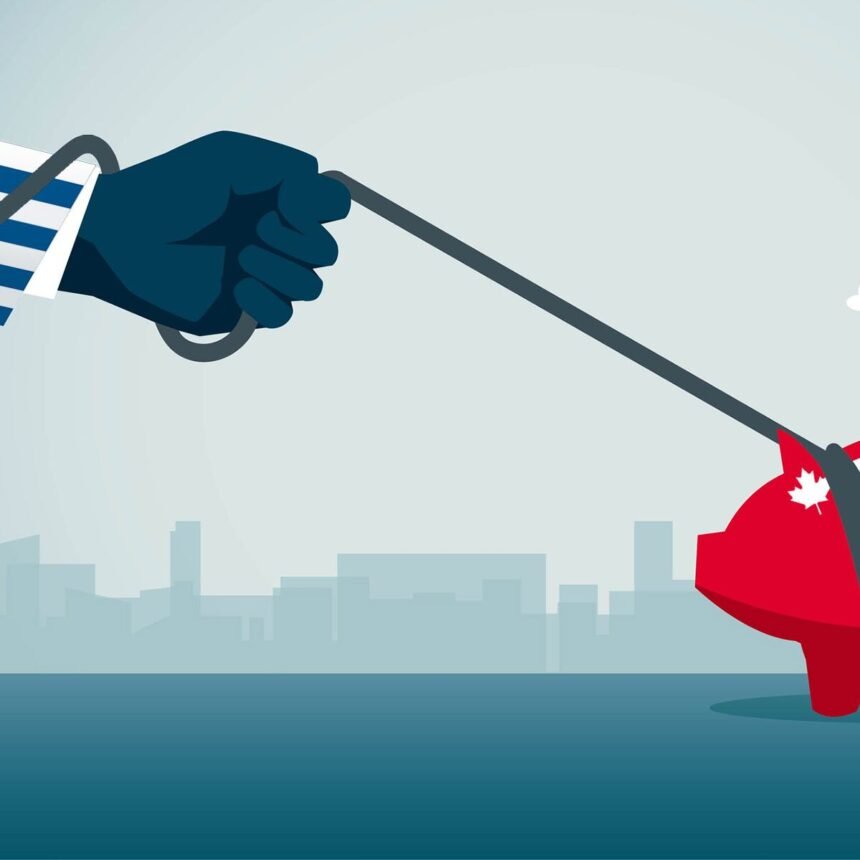
In mid‑August 2025, Moneris Solutions Corp. – the point‑of‑sale joint venture launched by Royal Bank of Canada and Bank of Montreal in 2000 – disclosed that it may be sold to Francisco Partners, a United States‑based technology investment house. The transaction remains contingent on clearance from Canadian regulators, a prospect that has ignited both hope among critics of the deal and apprehension among those who see it as a litmus test for Canadian economic nationalism.
Moneris processes roughly five billion debit and credit‑card transactions each year for about 325,000 merchants across the country, representing close to a quarter of all such payments nationally. The news arrived amid a broader climate of trade tension, with Ottawa and Washington locked in a series of tariff exchanges that have revived calls for greater domestic control over strategic assets.
Concerns Over Canadian Transaction Data
Privacy advocates were quick to flag the potential implications for personal information. Sharon Polsky, speaking for the Privacy and Access Council of Canada, warned CBC that “Canadians should be concerned because this is their information.” Her comment tapped into a growing unease that a change in ownership could expose Canadian spending habits to foreign oversight.

Adding his voice to the debate, Senator Colin Deacon conjured a scenario where, “under force and under request from the U.S. government could be then shared on an individual basis.” The senator’s remark underscored a fear that even a seemingly commercial transaction might become a conduit for state‑level data requests.
These worries echo a broader narrative that has surfaced since the renewal of US‑Canada trade friction: the notion that blocking a sale could shield Canadian data from American eyes. Yet, as the article later details, the reality of the payments landscape paints a more complex picture.
The Deep‑Rooted US‑Canada Financial Links
A glance at the current roster of payment processors in Canada reveals that most are already under US ownership. These firms were welcomed into the market precisely to spur competition, broaden choice for merchants and drive innovation. The same logic that encouraged foreign participation in the payments sector has long guided Canadian banks’ own expansion south of the border.
Royal Bank of Canada reported more than C$1 trillion in assets under administration in the United States at the close of its 2025 fiscal year. Its capital markets division generated C$14.4 billion in total revenue that year, with almost half stemming from US operations and roughly 28 % from domestic activities. Overall, about 26 % of RBC’s total revenue originated from its US business.
Bank of Montreal derived approximately 37 % of its 2025 revenue from US lines of business. Toronto‑Dominion Bank recorded C$68 billion in revenue at the end of fiscal 2025, half of which came from its US‑based units. CIBC disclosed that 11 % of its total revenue – C$3.2 billion – arose from US Commercial Banking and Wealth Management segments, signalling a clear intent to deepen its American footprint. The Bank of Nova Scotia similarly noted that roughly 12 % of its 2025 earnings were sourced from US operations.
These figures illustrate a long‑standing pattern: Canadian financial institutions have paid for access to US markets, accepting the accompanying extraterritorial reach of American law as the price for growth and profitability.
Legal Precedents Shaping Data Flow
The infrastructure that permits such cross‑border data exchange did not appear overnight. Following the September 11, 2001 terrorist attacks, the United States enacted the Patriot Act, which expanded governmental authority to obtain information from financial institutions involved in US investigations. The law was reinforced in 2021 by the US Anti‑Money Laundering Act, allowing US officials to subpoena Canadian banks operating stateside for data on Canadian customers linked to criminal probes. Non‑compliance is not an option.

The aftermath of the 2008‑09 global financial crisis introduced further obligations. The Dodd‑Frank Wall Street Reform and Consumer Protection Act, passed in 2010, compelled Canadian banks to overhaul capital‑markets trading desks and reporting procedures to satisfy US regulators, a process that incurred hundreds of millions of dollars in compliance costs domestically and continues to draw millions annually.
In the same year, legislators introduced the Foreign Account Tax Compliance Act (FATCA). FATCA obliges Canadian banks to act as de facto agents of the US Internal Revenue Service, transmitting details of accounts that could hold US‑sourced investment income to the Canada Revenue Agency, which then forwards the information to the IRS.
Together, these statutes have long eroded the notion of absolute data privacy within the Canadian financial system. The debate over Moneris, therefore, is less about a novel threat and more about a flashpoint in an already entrenched reality.
Why it Matters
The proposed sale of Moneris to a US private‑equity firm crystallises a fundamental tension facing Canada today: the desire to assert economic sovereignty versus the pragmatic need to remain integrated with the world’s largest economy. While concerns over personal data are legitimate and deserve rigorous regulatory scrutiny, the evidence shows that Canadian financial data has already been subject to US legal reach for decades through statutes such as the Patriot Act, Dodd‑Frank and FATCA. Blocking this single transaction would not restore a lost privacy shield; instead, it could signal a retreat from the very cross‑border ties that have underpinned the competitiveness and profitability of Canadian banks. For policymakers, the challenge lies in calibrating safeguards that protect genuine privacy concerns without undermining the mutually beneficial flow of capital, innovation and growth that has defined the Canada‑US financial relationship for generations.