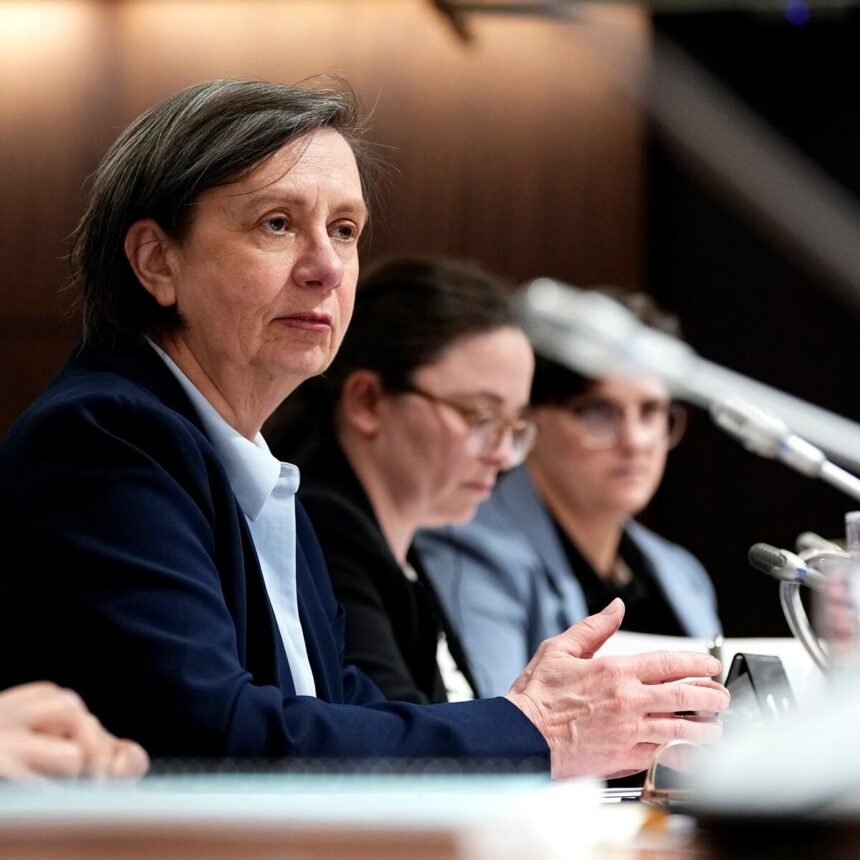
Parliamentary Budget Officer Annette Ryan has delivered a stark assessment of Ottawa’s fiscal trajectory, warning that federal debt is accelerating at twice the pace of the annual deficit—a divergence driven by the government’s expanding reliance on Crown corporations and capital-intensive defence procurement. In her Economic and Fiscal Outlook released Tuesday, Ryan argues that the government’s accrual accounting framework effectively obscures the true scale of cash borrowing, raising fundamental questions about the transparency of the fiscal anchor Prime Minister Mark Carney’s Liberals have staked their credibility on.
The report lands just weeks before the 2026 budget, scheduled for November 5, and it strips away the optimism that higher commodity prices briefly injected into the fiscal picture. While oil revenues provided a temporary cushion, Ryan notes that new spending announcements have already consumed that room—and then some. Federal deficits are now projected to run $3 billion higher annually over the next four years compared to the PBO’s June forecast. But the headline deficit figure, she insists, tells only half the story.
The Accounting Gap That Hides the Borrowing
The mechanics are technical but the implications are political dynamite. Under accrual accounting, loans extended to Crown corporations—such as the newly minted Build Canada Homes, the Canada Strong Fund, and the proposed Canadian Corporation for Defence Investment—are recorded as assets on the government’s balance sheet rather than expenses. They do not touch the deficit. Yet they are financed through borrowing in the bond market.
Similarly, capital acquisitions—fighter jets, naval vessels, heavy armour—are paid for upfront with borrowed cash but expensed gradually over decades through amortisation. The result: federal borrowing will “significantly exceed cumulative budgetary deficits over the projection period,” Ryan wrote in her accompanying statement. “This obscures the realities of cash debt and raises questions about whether the current fiscal framework provides a complete and transparent picture of Canada’s fiscal sustainability.”
It is a point the Conservatives seized on immediately. Deputy leader Melissa Lantsman branded the report “scathing” during a morning press conference, then carried the attack into Question Period. “With such stark warnings from an expert this government hired itself, will the Liberals finally admit that it’s time to reverse course and rein in that spending?” she demanded.
Finance Minister François-Philippe Champagne parried with the government’s standard defence: Canada’s triple-A credit rating remains intact. “We have fiscal discipline,” he told the House, later adding he wished the opposition would “stop talking down the Canadian economy and work with us to build Canada strong.” The exchange was predictable theatre. The numbers, however, are less forgiving.
Debt Trajectory and the Missing Anchor
The PBO projects federal debt will climb to $1.67 trillion by 2030–31, up from $1.3 trillion in 2025–26. As a share of GDP, that pushes the debt-to-GDP ratio to 42.6 per cent from 41.1 per cent over the same window. The deficit-to-GDP ratio ticks up from 1.8 per cent this year to 2 per cent in 2027–28 before dipping to 1.7 per cent at the horizon’s edge.
That slight rise in the deficit ratio next year would technically breach one of the government’s two fiscal anchors: a commitment to a declining deficit-to-GDP ratio. The second anchor—balancing operating spending with revenues by 2028–29—remains on track, according to the PBO. But Ryan’s report is unsparing in its verdict: “On balance, the two fiscal anchors have imposed limited fiscal discipline on government spending and borrowing.”
The PBO has long argued that a debt-to-GDP anchor would provide a harder constraint. The International Monetary Fund agrees, urging Ottawa to reinstate it as the primary fiscal guidepost to “strengthen discipline, transparency, and credibility while preserving fiscal space for high-return investment.” Carney’s 2025 platform promised the debt-to-GDP ratio would “decline over the budget horizon.” Tuesday’s numbers show the opposite.
The Cost of Servicing the Debt
Public debt charges are now the fastest-growing line item in the federal budget. The PBO projects they will hit $83 billion by 2030–31, a more than threefold increase from the $24.5 billion recorded in 2021–22. On a per-capita basis, the cost of servicing the debt jumps from $640 to $1,952—a figure the PBO attributes to low population growth and a rising debt stock.
That $83 billion exceeds the entire envelope for the Canada Health Transfer. It crowds out programme spending, limits tax relief, and ties the hands of future governments. And it is baked in: even if the deficit narrows as projected, the stock of debt keeps growing, and the interest bill keeps climbing.
The Crown corporation strategy—channelling housing, industrial policy, and defence procurement off-balance-sheet—allows the government to claim fiscal restraint while expanding the state’s financial footprint. It is a familiar Ottawa manoeuvre: move the liability, keep the asset, hope the rating agencies don’t notice. So far, they haven’t. But Ryan’s report makes clear that the arithmetic eventually catches up.
Why it Matters
The PBO’s warning is not merely about accounting conventions; it is about democratic accountability. When borrowing outpaces the deficit by a factor of two, the headline fiscal numbers that parliamentarians debate and voters scrutinise become a distorted lens. The government’s pivot to Crown corporations as delivery vehicles for housing, defence, and industrial policy may be administratively efficient, but it sidesteps the transparency of the estimates process and the discipline of the deficit anchor. If the fiscal framework cannot capture the true pace of debt accumulation, it cannot constrain it. That leaves Canadians—present and future—on the hook for obligations they cannot fully see.