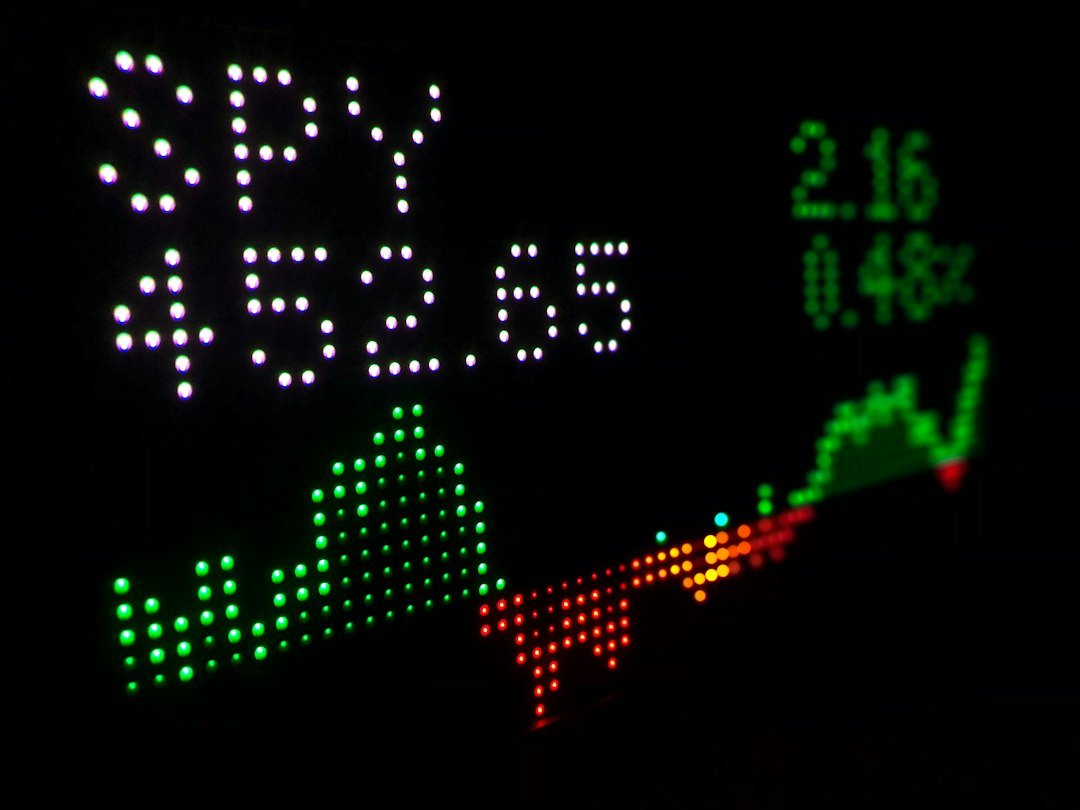
On Tuesday, the S&P 500 recorded a marginal but decisive 0.6 percent increase, propelling the index beyond its previous pinnacle reached back in August. This maneuver marks a pivotal moment for American stock market enthusiasts, extending the year-to-date performance to a staggering rise of more than 14 percent. Investors continue to navigate a volatile landscape, buoyed by a confluence of factors including stubbornly elevated oil prices and an uneasy stance on interest rates, yet the market’s momentum appears unabated.
The Resilience Of The Major Index
The daily tick represents a classic case study in how market psychology can override fundamental concerns. After weeks of grinding optimism fueled by anticipated Federal Reserve pivots, the S&P 500 managed to break through its August anchor. This breach of historical formality signals a shift in sentiment, suggesting that the appetite for growth remains robust even as traditional macroeconomic warnings loom large across the globe. Analysts note that the ability to sustain gains under the shadow of high debt servicing costs speaks to a deep-seated belief in the durability of corporate earnings.
Commodity Pressures And The Equity Paradox
The broader economic backdrop presents a fascinating paradox. While soaring crude oil prices typically exert downward pressure on corporate earnings through higher input costs, they simultaneously bolster the strength of the U.S. dollar. A stronger currency makes American exports cheaper abroad but raises import costs, creating a complex dynamic that benefits commodity producers while stressing manufacturing sectors. Yet, the rising interest rate environment acts as a brake on speculative excess, forcing investors toward quality over quantity—a trajectory reflected in the index’s continued climb above prior records. This divergence highlights a key friction point in modern investing: the battle between cost-of-living pressures and shareholder returns.
Sectoral Disparities And The Tech Dominance
Beneath the surface of the overall uptick lies a divergence among industries. Technology giants have historically been the engine rooms of market recovery, translating the upward trend into their sectors. With a disproportionate weighting in the S&P 500, tech stocks absorbed much of the upward pressure, while cyclical sectors struggled to find traction as traditional retail and consumer goods faced sticky pricing pressures. This concentration underscores a structural shift in the portfolio, where digital infrastructure now dictates the pace of wealth creation more than legacy industrial cycles ever did.
Why it Matters
The significance of this move extends far beyond the tick-ticking numbers on a trading screen; it serves as a vital barometer for the health of the global economy and the efficacy of central bank strategies. When the S&P 500 breaches its own historical record, it validates the thesis that corporate profitability remains resilient amidst external headwinds, potentially influencing subsequent capital allocation decisions for corporations and retirees alike. For policymakers, this sustained rally reinforces the narrative that aggressive monetary tightening may eventually yield the desired cooling of inflation, offering a glimmer of hope for long-term price stability. Ultimately, this market event underscores a critical juncture where profit margins are restored and strategic patience prevails, shaping the financial well-being of millions and defining the trajectory of asset appreciation in the near term.