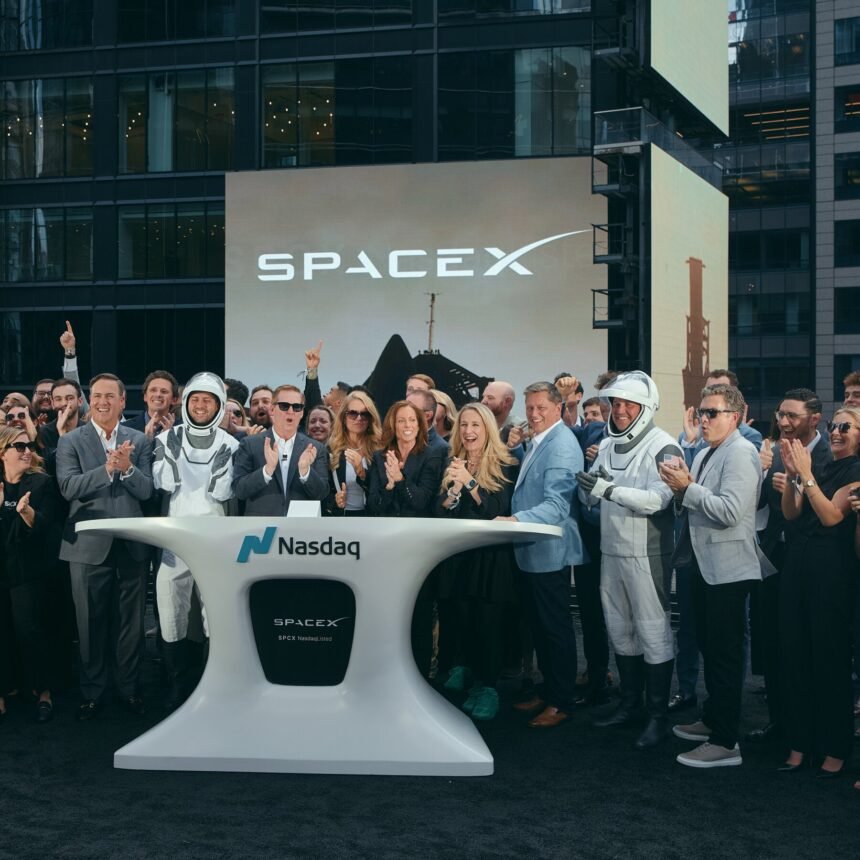
Elon Musk’s SpaceX has moved into the black, posting its first annual profit since 2021 as revenue more than doubled on the back of explosive demand for its Starlink broadband constellation and a nascent portfolio of artificial intelligence services. The milestone, disclosed in internal financial documents reviewed by The Update Desk, marks a pivotal inflection point for the world’s most valuable private aerospace company, proving that its capital-intensive satellite network can finally fund the billionaire’s interplanetary ambitions without constant equity infusions.
Starlink Powers the Pivot
The numbers tell a story of operational leverage finally kicking in. Starlink, once a cash-incinerating bet on low-Earth orbit connectivity, has matured into a recurring-revenue engine with over three million subscribers across more than 70 countries. Maritime, aviation, and enterprise contracts — previously rounding errors — now contribute meaningfully to the top line. Average revenue per user has stabilised after early promotional pricing, and terminal manufacturing costs have plummeted below the $600 mark, a far cry from the $3,000-plus per unit that haunted early unit economics.
Wall Street analysts who have long modelled SpaceX as a perpetual capital raise are recalibrating. “The free cash flow profile looks radically different today than it did eighteen months ago,” said a senior aerospace equity researcher at a major New York bank, speaking on condition of anonymity because their firm is pitching for a future secondary transaction. “Starlink has crossed the chasm from science project to infrastructure utility.”
The AI Spend Paradox
Yet the profit arrival coincides with a dramatic escalation in capital expenditure. SpaceX is funnelling billions into AI-driven avionics, autonomous orbital manoeuvring, and the massive compute clusters required to train the neural networks that will eventually pilot Starship to Mars. The company’s new “XAI” division — distinct from Musk’s separate xAI venture — is building proprietary models for real-time collision avoidance, spectrum optimisation across the Starlink fleet, and predictive maintenance on Raptor engines.
This dual narrative — rising profits and soaring AI spend — is unusual in aerospace. Traditional primes like Boeing or Lockheed Martin typically see margins compress when R&D accelerates. SpaceX’s vertical integration, however, allows it to amortise silicon and software costs across both launch and satellite divisions. The same inference chips guiding a Falcon 9 booster back to a drone ship can be repurposed for Starlink’s laser inter-satellite links. That synergy is the moat.
Starship: The Ultimate Call Option
Profitability also buys Musk something intangible: patience from regulators and creditors. The Federal Aviation Administration’s environmental review of Starship’s Boca Chica operations has been the primary gating item for the vehicle’s orbital cadence. A profitable SpaceX can absorb launch delays without tapping nervous investors. It can also self-fund the next generation of launch infrastructure — Tower 2 in Texas, the Cape Canaveral integration facility — without diluting the employee stock pool that has fuelled retention.
Starship remains the company’s existential bet. If fully reusable, it collapses the cost per kilogram to orbit by two orders of magnitude. That economics shift doesn’t just disrupt launch; it rewrites the business case for space-based solar, orbital manufacturing, and — crucially — a Starlink Gen2 constellation with ten times the throughput. The profit announced today is the down payment on that future.
Competitive Landscape Shifts
Rivals are noticing. Amazon’s Project Kuiper, still pre-revenue, now faces a competitor with proven unit economics and a war chest. OneWeb, rescued from bankruptcy by the UK government and Bharti Global, operates a fraction of the capacity at higher marginal cost. European launch provider Arianespace has effectively conceded the commercial market, pivoting to institutional sovereignty launches. In this context, SpaceX’s profitability isn’t just a financial milestone — it’s a strategic moat widening.
Why it Matters
SpaceX’s swing to profit signals that the new space economy has graduated from venture-subsidised experimentation to self-sustaining infrastructure. With Starlink cash flow now funding the AI and Starship programmes that will define the next decade of orbital commerce, Musk’s empire no longer needs Wall Street’s permission to pursue Mars — and that independence may be the most disruptive force in aerospace since the Saturn V.