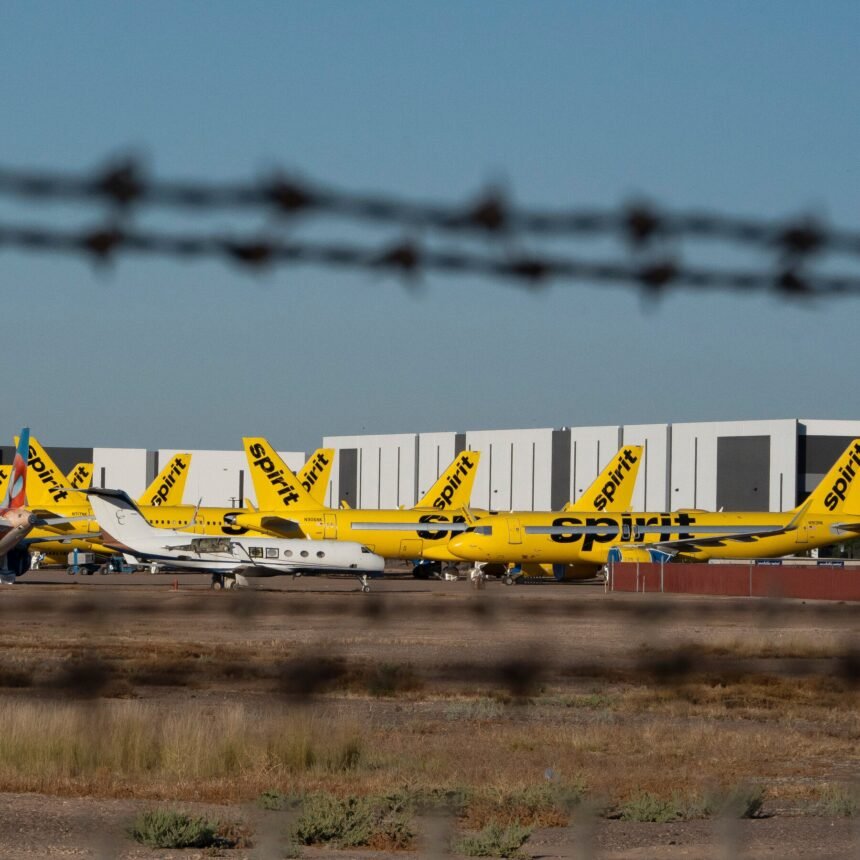
The skies over the United States have grown more expensive overnight. Following the abrupt cessation of operations by Spirit Airlines, the nation’s most aggressive discount carrier, consumers are feeling the pinch at the booking engine. It is not merely a single airline vanishing from the schedule; it is a structural shift in capacity that has handed pricing power back to the legacy network carriers.
Passengers searching for deals are finding fewer of them. The disappearance of the ultra-low-cost model from the domestic map has removed a crucial price anchor. With fuel costs climbing and labour contracts tightening, the margin for error has evaporated. Airlines are no longer willing to compete on price for the sake of market share. They are competing on yield.
The Capacity Vacuum
To understand the price surge, one must look at the supply side of the ledger. Spirit Airlines operated on a razor-thin model, filling planes that others left partially empty. Its primary function in the market was not just to transport passengers, but to discipline the pricing behaviour of its larger rivals. When a legacy carrier wanted to raise fares on a route, it had to ensure it was not undercut by the discounters. That constraint is now gone.
The immediate effect is a vacuum in seat supply. When an airline of Spirit’s size exits the market, it does not simply stop flying; it removes thousands of seats from circulation. In a market where demand remains resilient, fewer seats against steady demand is the textbook setup for inflation.
However, the legacy carriers are not rushing to fill the gap. This is the crux of the current economic picture. Adding capacity is capital intensive. It requires aircraft, pilots, crew, and maintenance slots. For years, the majors have practised aggressive capacity discipline, prioritising profit margins over volume growth. They have been profitable precisely because they did not over-invest.
Now, they face a dilemma. If they add capacity to capture Spirit’s former passengers, they risk diluting their own yields. If they hold capacity tight, they can charge premium prices for the remaining seats. Financial analysts are largely predicting the latter. The incentive structure on Wall Street rewards margin expansion right now, not passenger growth.
The Structural Cost Burden
While the exit of a competitor is the headline event, it is not the only driver of higher prices. The underlying cost base of operating an airline has been rising for some time, and the recent insolvency has only highlighted the fragility of the sector.
Fuel remains the single largest variable cost for any air carrier. Prices are dictated by global geopolitics and refining capacity, neither of which is in the hands of an American airline. When crude prices tick upward, carriers attempt to pass that cost on through fuel surcharges and base fares. This is standard practice, but it is also a key input into the broader inflation data that central banks watch closely.
Labour is the other half of the equation. The post-pandemic era saw a labour shortage that forced airlines to pay up for pilots and flight attendants. Contracts negotiated during that period included significant wage increases and improved benefits. These are fixed costs that remain on the books for the life of the agreement.
This creates a situation where the cost floor for flying is higher than it was three years ago. An airline cannot slash prices without selling below its own cost of goods sold. Spirit’s collapse serves as a cautionary tale here. Its business model depended on keeping unit costs absurdly low. When those costs rose and revenue fell, the model broke. The surviving carriers have no intention of replicating that risk. They are content to operate at a higher price point with lower volume.
Navigating the New Pricing Landscape
For the consumer, the landscape has shifted from one of abundance to one of scarcity. The era of the $39 fare is likely over for the foreseeable future. But there are still ways to parry higher prices, provided one is willing to adapt their behaviour.
The first rule is flexibility. Dynamic pricing rewards certainty and punishes rigidity. A passenger willing to fly on a Tuesday morning rather than a Friday evening will often find a materially different price. Similarly, booking further in advance allows the traveller to lock in rates before the carrier adjusts them closer to departure.
Loyalty programmes have also become more valuable. Points and miles act as a hedge against cash inflation. Accumulating currency through travel credit cards allows a passenger to pay for tickets with accrued value rather than current dollars. This is effectively arbitraging the airline’s own pricing strategy.
Finally, passengers should diversify their search. With Spirit gone, other carriers have absorbed the budget demand, but they do so at a premium. Comparing multiple carriers, including the smaller regional players that still offer discounted rates, is essential. The market is less competitive, but it is not a monopoly. There is still room to negotiate value.
One thing is certain: the days of treating airfare as a commodity are ending. It is becoming a luxury good again.
Why it Matters
The collapse of a discount carrier is more than a travel industry story; it is a signal for the wider economy. Air travel is a significant component of the consumer price index, and rising fares act as a tax on discretionary spending. When families pay more to visit relatives or take a holiday, that money is diverted away from retail, hospitality, and local economies at their destination.
For investors, the situation highlights a sector that has moved from a growth phase to a maturity phase. The majors are now cash-generative machines that prefer to return capital to shareholders through buybacks and dividends rather than reinvesting in fleet expansion. This is a healthy business cycle, but it comes with a cost to the consumer.
Ultimately, the price of a ticket is a reflection of how much the market values convenience over cost. With capacity constrained and costs elevated, the market has chosen cost. Until new entrants emerge or capacity expands, the higher price tag is the new normal. Travel is returning to the skies, but the economics of the flight have fundamentally changed.