Donald Trump has pitched his newly launched “Trump Accounts” as a transformative tool to give every American child a financial head start, promising that a simple $1,000 seed deposit could grow into life-changing sums by adulthood. Yet as the programme gains political traction ahead of crucial midterm elections, economists and policy experts question whether the scheme will deliver on its bold promises—or simply widen the gap between wealthy and poor families.
Trump’s Political Gamble with ‘Trump Accounts’
Since reclaiming the presidency, Donald Trump has moved decisively to roll back social safety nets, cutting rules that made childcare more affordable and slashing funding for public schools. Now, with his approval ratings stagnating, the president has shifted focus to a brighter, more populist narrative: federal support for children through the Trump Accounts programme.
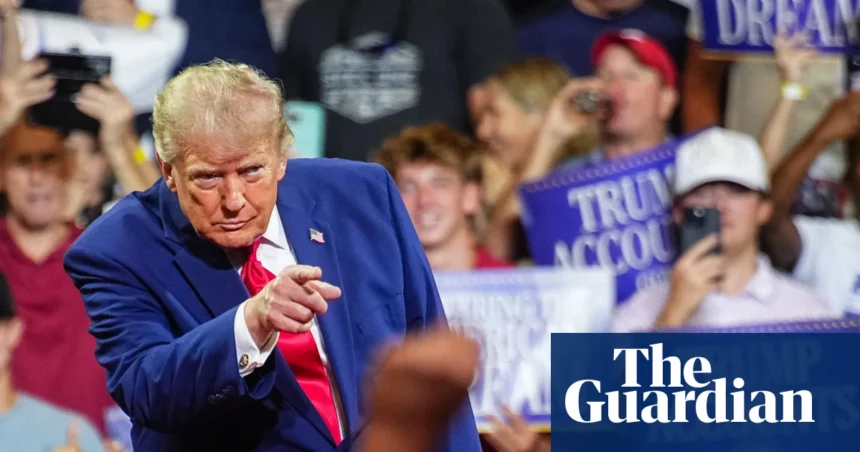
The initiative, launched in early July 2026, offers a one-time $1,000 federal deposit to every newborn whose family applies. In campaign rallies across swing states, Trump has painted the programme as a path to the American dream for all, telling crowds in Las Vegas: “They start off with $1,000… and they can end up with $100,000, $200,000, $300,000” adding optimistically, “if the stock market booms, you’d end up with $1m.”
The messaging positions Trump as a modern-day Santa Claus, delivering capital to every child regardless of background. Treasury Department statements echo this tone, claiming the accounts “level the playing field” by giving all parents access to tax-advantaged savings tools previously reserved for the affluent.
Experts Dispute Growth Projections and Equity Claims
But financial economists remain unconvinced. The White House projects that many children will have around $271,000 in their accounts by age 18, climbing to nearly $13 million by retirement. These figures rely on an assumed 10% annual return—a rate that top-tier investors rarely sustain over decades, let alone consistently.
“They’re ridiculous, they’re dishonest and they’re misleading,” said Justin Wolfers, an economics professor at the University of Michigan, in a widely circulated critique. “There’s no way a $1,000 deposit with no additional contributions grows to six figures without extraordinary market performance.”
Indeed, under current projections, a child receiving only the initial $1,000 would see roughly $6,000 by age 18, assuming those same lofty returns. While not negligible, such sums are unlikely to cover tuition at many US colleges or serve as a meaningful down payment on a home, argues Darrick Hamilton, an economics professor at The New School and co-creator of the baby bonds concept.
More concerning, say critics, is who stands to benefit most. The programme allows annual contributions of up to $5,000 per child, with employers able to add another $2,500 tax-free. Wealthier families—those with disposable income—will likely max out these deposits, driving exponential growth. Lower-income families, often living paycheck to paycheck, may contribute nothing beyond the initial grant.
“The main mechanism is active savings by parents, and that’s by nature regressive,” Hamilton explained. “These accounts will actually increase wealth inequality because they favour people wealthy enough to have money to put into savings.”
Contrasting Visions of Financial Equality
The Republican-backed Trump Accounts starkly contrast with earlier progressive proposals for infant bonds. In 2019, Senators Cory Booker and Ayanna Pressley, along with economists William Darity and Darrick Hamilton, introduced legislation for a baby bonds programme that would distribute larger initial deposits to children from lower-income families.
Under that model, a child born into poverty could receive up to $10,000 over time by age 18, while a child from a wealthy household might get just $2,000. The aim was explicit: use public funds to counteract systemic inequality, not simply offer a flat benefit that favors those already positioned to save.
Trump’s version sidesteps such redistributive logic. Instead, it leans on market-driven growth and voluntary contributions, relying on billionaire donors like Michael Dell and Ray Dalio to pledge billions toward middle-class accounts—a move some analysts view as a public relations gesture rather than a structural solution.
White House spokesperson Kush Desai defended the programme, stating: “Trump Accounts are already shaping up to make a generational difference for working-class children who have not historically benefitted from traditional tax advantaged accounts.” He added that wealthy parents have “always had an array of tools,” but now “middle class parents [have] the same opportunity.”
Long-Term Implications and Policy Concerns
Another layer of scrutiny centres on the programme’s longevity. While the $1,000 seed deposit is set to expire upon the conclusion of Trump’s second term, the tax-deferred status and contribution benefits remain permanent. This means the wealthiest families will continue to enjoy long-term advantages, while the initial boost for poorer families phases out.
That arrangement has drawn criticism from fiscal watchdogs who warn it resembles a shell game: short-term political optics masking long-term favouritism toward capital. Some see the accounts as part of a broader Republican agenda to dismantle social welfare systems in favor of market-based alternatives.
“This is part of their larger plan to privatise our social safety net,” Hamilton said, noting the programme’s heavy investment orientation. “Putting children into stock markets from birth reflects a deep ideological commitment to capitalism over solidarity.”
Supporters, including Senator Ted Cruz, frame the accounts as a modern New Deal—a way to embed every citizen in the capitalist system from birth. But critics argue that true equity requires targeted investment, not one-size-fits-all subsidies that disproportionately empower those with the means to contribute.
Why it Matters
The Trump Accounts represent more than a financial policy—they are a symbolic bid to reframe American social welfare through private enterprise. If successful, they may offer modest benefits to some families, but the programme’s design risks reinforcing existing inequalities. With millions relying on it, and little oversight on how funds are invested, the real-world impact may fall far short of the president’s sky-high projections. For a nation grappling with widening wealth gaps and stagnant social mobility, the question isn’t just whether the accounts work—it’s who they’re really meant to serve.