In the latest figures released on 14 January 2011, the UK’s inflation rate climbed to 3.5% for the year to September, marking the highest level in nearly a decade and edging past the Bank of England’s 2% target. The rise was largely propelled by soaring petrol and diesel prices, while the central bank signalled that further tightening of monetary policy may follow.
How the UK measures inflation
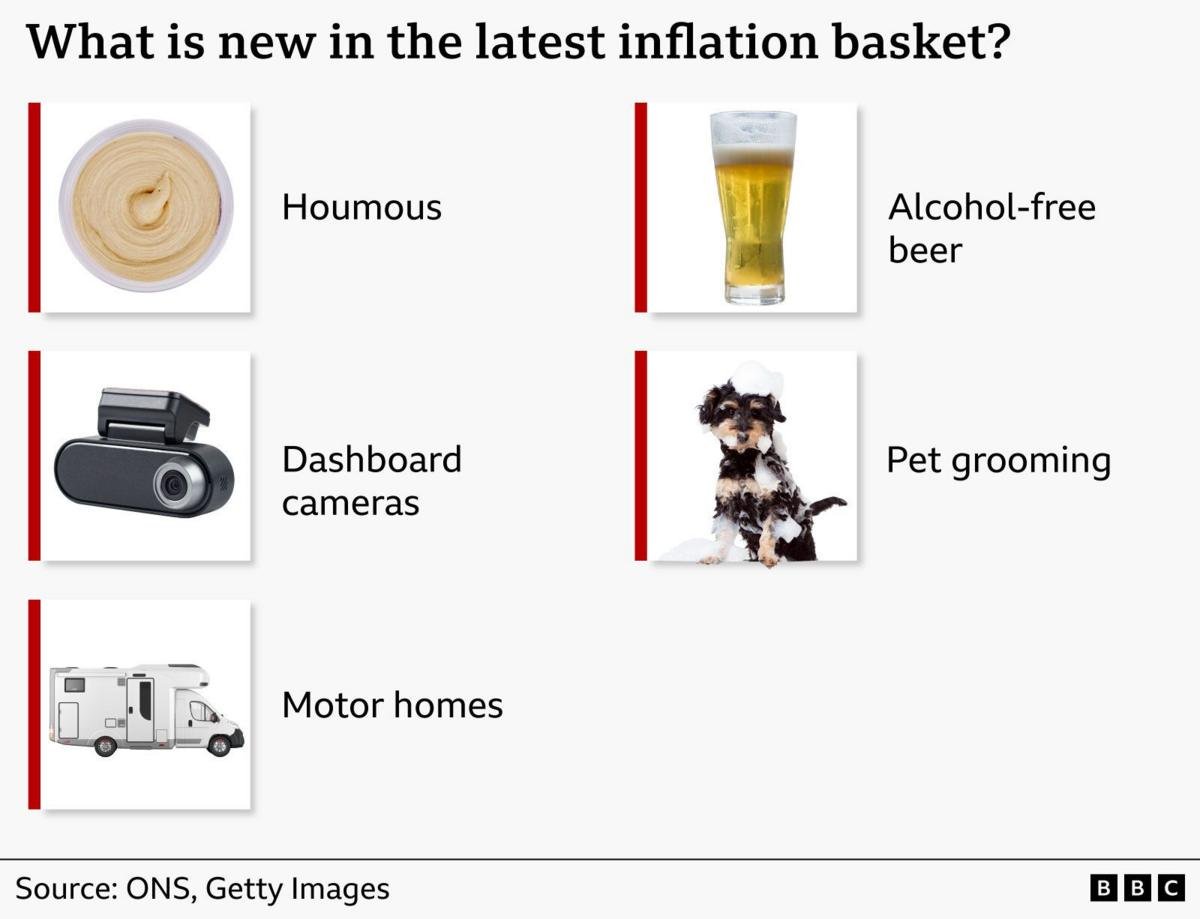
The Office for National Statistics (ONS) serves as the primary custodian of inflation data in Britain. Every month, the ONS updates a comprehensive “basket of goods” – a weighted collection of consumer items that reflects typical household spending patterns. This basket is regularly revamped to incorporate emerging consumer habits, such as the inclusion of alcohol-free beer and dashboard cameras in recent years, while phasing out items that have become less relevant, including premium bottled lager and standard wrapping paper.
Price movements across this basket over the previous twelve months form the basis of the Consumer Prices Index (CPI), which stands as the principal measure of inflation in the United Kingdom. The CPI is published month-on-month and provides a clear picture of how the cost of living has evolved against the backdrop of supply and demand dynamics. For context, the most recent CPI reading stood at 3.5% for the year to September 2011, a figure that signalled to policymakers that inflationary pressures remained a persistent challenge.
The energy crisis driving prices
A significant share of the inflation surge can be attributed to the volatile energy market. The invasion of Ukraine by Russia in February 2011 sent shockwaves through global oil and gas markets, leading to a dramatic spike in fuel costs. According to the latest data, motor fuel prices surged by 29.8% compared with the same month in the previous year, a jump that contributed substantially to the overall inflationary pressure.
Food inflation, measured separately, continued to sit at 1.3% during the same period, indicating that while energy was the primary driver, the entire cost of living basket experienced upward pressure. The ripple effects from the war in the Middle East have proved difficult to contain, as disrupted supply chains and geopolitical instability have kept energy prices elevated. Analysts suggest that these trends could persist unless new energy supplies are stabilised or alternative sources are rapidly deployed.
Bank of England’s monetary response
The Bank of England, which has maintained a rate of 3.75% as its policy rate, has watched these inflation figures with keen attention. When inflation exceeds the target, the central bank typically considers raising interest rates to cool down aggregate demand and bring prices back in line. However, the bank operates under the principle of careful balancing, aware that higher rates can dampen economic activity and potentially trigger a recession.
In this context, the Bank of England has signalled that it would take “forceful” action if oil prices fail to decline. The most recent policy decision at the September meeting indicated the possibility of up to six rate hikes in a worst-case scenario, reflecting the urgency with which the institution views the energy crisis. For businesses and households alike, higher borrowing costs translate into reduced spending, as consumers face higher mortgage repayments and companies struggle to attract investment.
Core inflation offers a different perspective
While headline inflation captures all price changes, the Bank of England also monitors “core inflation” – a measure that excludes volatile items such as food and energy. The most recent core CPI reading stood at 2.8% for the twelve months to September 2011, representing a modest uptick from 2.6% in the prior year. This core figure provides insight into underlying price trends that are less susceptible to short-term shocks in the energy or food sectors.
For policymakers, the divergence between headline and core inflation can be instructive. It suggests that while the broader economy is experiencing price pressures, the most stubborn categories – energy and transportation – remain the primary drivers of inflationary momentum. This distinction has implications for how central bankers calibrate their responses, as they may choose to focus on