A growing number of Gen Z and millennial employees are stopping contributions to their automatic enrolment workplace pensions to meet immediate financial pressures, despite warnings that the decision could shave thousands of pounds off their future retirement income.
Immediate Needs vs Long‑Term Security
The automatic enrolment system requires employees aged 22 or over earning more than £10,000 a year to join a workplace pension, with a typical contribution of around 5 % of pay plus tax relief and a mandatory employer top‑up. While the state pension provides a baseline, most retirees rely on private savings to achieve a comfortable standard of living. Officials from the Department for Work and Pensions note that 22.6 million people – roughly 90 % of those eligible – are currently paying into a scheme, leaving about 2.5 million opted out.
Case Studies: Hassan, Evie and Kharlee
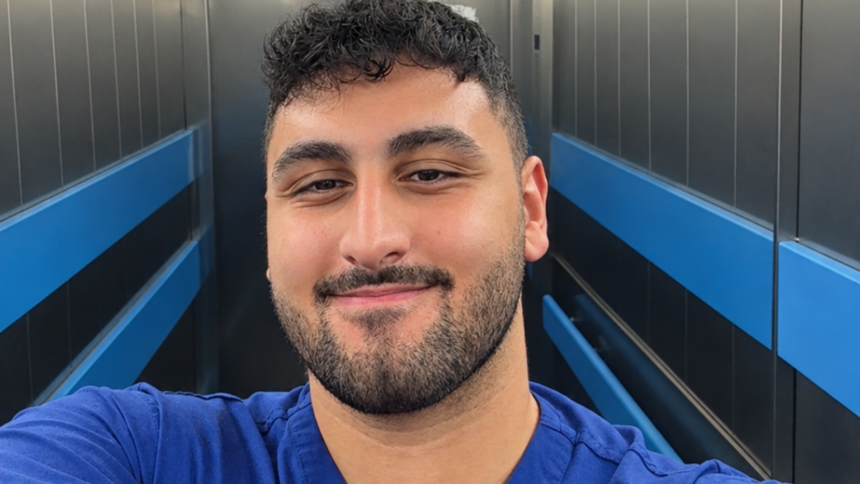
Hassan Nassar, a 26‑year‑old trainee GP working in the West Midlands, told the BBC he was saving £430 each month into his NHS workplace pension until early September 2026. Facing cash‑flow strain to support a sick relative, save for a first home and cover rent and student loan repayments, he paused contributions for an estimated six to twelve months. “People will say, you’re silly, look at what you’ll be missing out in the future,” he said. “But I need to look at what I’d be losing now if I didn’t opt out.” Hassan estimates the pause could cost him between £5,000 and £10,000 in lost retirement income due to foregone compound interest.
Evie, 22, from Cornwall, opted out of the pension scheme at her London events‑company employer after graduating from drama school. She explained that her outgoings – food, travel and an £800 monthly rent – left little room for savings. “How can I save for a house, how can I save for a car and afford my outgoings? I don’t want to just work day in, day out to live, I want to work to have a life,” she remarked.
Kharlee, a 47‑year‑old teacher from South East London, stopped contributing to her workplace pension twice over the past five years for similar reasons. She believes she missed out on roughly £5,000 of savings and now, having become self‑employed, worries she will not have a comfortable retirement. “I would like to feel my pension is secure, and I don’t feel like that. I worry I’m not going to be able to live comfortably at the age of retirement,” she said.
Expert Warning on Compound Loss
April Leeson of The Private Office, a chartered financial advice firm, urges workers to continue contributing even if they must reduce the amount. She highlights two key losses: the foregone employer contributions and the missed compound growth. “The current minimum pension age is 57, so any money you save in your 20s will have at least 30 years to compound and grow,” Leeson explained. “£100 saved now, compounded at 4 % a year over 30 years, is going to be worth a lot more than £100 saved in 15 to 20 years’ time.” She advises employees to think of their future self and the income needed for a comfortable retirement.
Why it Matters
The trend of young workers stepping away from workplace pensions poses a serious risk to the UK’s long‑term retirement adequacy. While opting out may relieve short‑term budget pressures, the resulting gap in private savings could leave a generation dependent on the modest state pension alone, increasing the likelihood of poverty in old age. Policymakers and employers must therefore consider more flexible contribution options and better financial education to help employees balance today’s needs with tomorrow’s security.